Casino Sites That Accept Trustly in Australia 2026: The Real Speed Test
 Available in AU
Trustly promises instant bank transfers without the usual friction. No e-wallet signup, no card details shared across a dozen merchant sites, just your existing bank login and a confirmation. For Australian players in 2026, that pitch lands somewhere between convenient and too-good-to-check. The method works, the deposits clear fast, but the gap between what offshore casino marketing says and what actually happens when you request a withdrawal is where most players learn the expensive lessons.
The Interactive Gambling Act 2001 means no Australian-licensed online casinos exist. Every site accepting Trustly deposits from Australians operates offshore — Curaçao, Malta, Kahnawake — and sits outside local regulatory oversight. Trustly itself is a legitimate payment processor, licensed in Sweden, but the moment it moves your money into an offshore casino account, Australian consumer protection stops at the border. Dispute resolution goes through the operator’s licensing jurisdiction, not a local tribunal. That structural reality shapes every choice you make about which Trustly casino to fund.
This breakdown ranks eight offshore operators by how Trustly actually performs at each one: withdrawal processing speed, realistic end-to-end timelines, transaction limits, currency conversion traps, and what happens when a deposit or payout stalls. No “instant withdrawal” claims repeated verbatim from the cashier page. Just the multi-stage process as it runs in practice, with the friction points flagged before you deposit.
Top Casino Sites Accepting Trustly in Australia 2026
The table below lists offshore operators by Trustly withdrawal speed — the metric that separates marketing from reality. Every operator here accepts Trustly deposits, but the gap between clicking “withdraw” and seeing funds in your Australian bank account varies from half a day to most of a week.
| Operator | License | Trustly Withdrawal Speed | Minimum Deposit | Daily Withdrawal Limit | Key Differentiator |
|---|---|---|---|---|---|
| PlayAmo | Curaçao (Direx N.V.) | 12 hours | AUD $15 | AUD $5,000 | Fastest Trustly processing, hybrid crypto support |
| LeoVegas | MGA + UKGC | 24 hours | AUD $10 | AUD $4,000 | Mobile-first design, MGM-backed since 2022 |
| Jackpot City | MGA + Kahnawake | 24-48 hours | AUD $10 | AUD $4,000 | 26 years operation, Microgaming exclusivity |
| Royal Panda | MGA + UKGC | 24-48 hours | AUD $10 | Not disclosed | Transparent bonus terms, LeoVegas sister brand |
| Skycrown | Curaçao (Hollycorn N.V.) | 1-3 days | AUD $30 | AUD $7,500 | Native AUD processing, highest daily limit |
| Spin Casino | MGA + Kahnawake | 24-48 hours | AUD $10 | AUD $4,000 | Jackpot City sister brand, identical backend |
| Playfina | Curaçao (Softgenius N.V.) | 1-3 days | AUD $30 | AUD $7,000 | Highest monthly limit (AUD $70,000) |
| Wild Fortune | MGA (Rabidi N.V.) | 1-5 days | AUD $30 | AUD $1,000 | Aggressive bonus (225%), lowest daily limit |
The “withdrawal speed” column shows Trustly processing time after the casino approves the payout. It excludes the casino’s internal pending period (0-24 hours) and your bank’s incoming credit time (0-48 hours). The full end-to-end timeline is covered in a later section, because “24-hour Trustly withdrawal” marketing usually translates to 48-72 hours in practice once you account for every stage.
PlayAmo Casino
PlayAmo runs under Direx N.V., a Curaçao operator managing multiple casino brands including Bitstarz and King Billy. The Curaçao eGaming license (8048/JAZ2020-013) sits a regulatory tier below Malta or UKGC oversight, but Direx has operated since roughly 2016 without major public scandals or unresolved dispute patterns surfacing in gambling forums. The site markets itself as a hybrid: traditional payment rails (Trustly, cards, e-wallets) sit alongside cryptocurrency options (Bitcoin, Ethereum, Litecoin), which attracts players who want flexibility without locking into one payment model.
Trustly withdrawal processing at PlayAmo advertises “within 12 hours” after casino approval, the fastest claim in this comparison. That 12-hour window is Trustly’s own processing, not the full journey from withdrawal request to funds landed in your Australian bank account. Casino approval adds 0-24 hours depending on whether KYC verification is already cleared, and your bank’s incoming transfer can sit pending for another 0-48 hours. Best-case total: 12 hours if everything aligns. Realistic total for a first withdrawal: 36-60 hours. Still faster than the 24-48-hour Trustly baseline at Malta-licensed competitors, which edges out to 72-96 hours end-to-end. Minimum Trustly deposit is AUD $15, slightly higher than the $10 baseline elsewhere. Daily withdrawal cap is AUD $5,000 with a weekly limit around $10,000 per third-party reports. The 3,000+ game library aggregates providers (Microgaming, NetEnt, Pragmatic Play, Betsoft), broader than Microgaming-exclusive operators but with less curation. PlayAmo’s Curaçao license means dispute resolution routes through Curaçao eGaming arbitration, not Malta’s player-protection framework.
LeoVegas Casino
LeoVegas Gaming plc started in 2011 as a mobile-first casino, won multiple industry awards for mobile design, then was acquired by MGM Resorts International in 2022 for USD $604 million. That acquisition brought major land-based casino capital and corporate oversight to what was already a large European operator. The dual Malta Gaming Authority and UK Gambling Commission licenses put LeoVegas in the highest regulatory tier among offshore operators serving Australia — both MGA and UKGC enforce strict financial solvency, game fairness, and player-protection requirements that Curaçao does not match.
The 6,000+ game library is the largest in this comparison, pulling from every major provider (NetEnt, Microgaming, Play’n GO, Pragmatic Play, Evolution for live dealer). The mobile app and mobile-optimised site remain the standout feature; LeoVegas built its brand on smartphone play before most competitors took mobile seriously. Trustly withdrawal processing runs at 24 hours after casino approval per operator claims, a middle-tier speed. Add casino pending (0-24h) and bank credit time (0-48h) for a realistic 24-72 hour total on first withdrawals. Minimum Trustly deposit is AUD $10, the baseline. Daily withdrawal limit starts at AUD $4,000 for standard accounts, reportedly higher for VIP tiers but exact VIP thresholds are not publicly disclosed. Customer support response times are faster than budget Curaçao operators, likely tied to UKGC regulatory requirements around complaint handling. The MGM backing since 2022 adds financial stability that newer Curaçao brands cannot match. If mobile casino experience is the priority and you can accept 24-72 hour withdrawal timelines, LeoVegas is the premium pick. The MGA + UKGC dual licensing also means clearer dispute resolution paths than Curaçao-only operators.
Jackpot City Casino
Baytree Interactive Ltd operates Jackpot City under dual Malta Gaming Authority (MGA/B2B/139/2007) and Kahnawake Gaming Commission licenses. The brand launched in 1998, making it one of the longest-running online casino operations still accepting Australian players. That 26-year track record is the key differentiator: you trade cutting-edge interface design for operational stability and a multi-decade history of processing withdrawals without collapsing or exit-scamming.
The game library is roughly 500 titles, heavily weighted toward Microgaming pokies and table games. Baytree/Jackpot City has a long-standing exclusive partnership with Microgaming, which means access to the Mega Moolah progressive jackpot network and other Microgaming-exclusive progressives not available at multi-provider aggregators like PlayAmo or Skycrown. If Microgaming’s back-catalogue (Immortal Romance, Thunderstruck II, etc.) is the draw, Jackpot City is one of the few operators still running Microgaming as the primary provider rather than a secondary supplement. The tradeoff is a narrower game selection compared to operators pulling from a dozen studios.
Trustly withdrawal processing sits at 24-48 hours after casino approval, the industry standard for MGA-licensed operators. End-to-end realistic timeline: 48-96 hours first withdrawal, 24-72 hours for subsequent withdrawals once KYC is cleared. Minimum Trustly deposit is AUD $10. Daily withdrawal baseline is around AUD $4,000, though Baytree’s terms allow negotiation for higher-volume players with established account history. The dual MGA + Kahnawake licensing means two separate regulatory bodies oversee the operation, which historically correlates with fewer unresolved disputes compared to single-license Curaçao operators. The welcome bonus structure offers up to AUD $1,600 split across the first four deposits, with 35x wagering requirements — standard terms, not the aggressive 45-50x some newer operators push. Jackpot City is the “safe, boring” pick: no 12-hour Trustly speed claims, no 5,000-game library, just reliable operation and the longest continuous track record in this comparison.
Skycrown Casino
Hollycorn N.V. launched Skycrown in 2022 under a Curaçao Gaming Control Board license, positioning it as an “Australian-friendly” offshore casino. The key structural advantage for Australian players is native AUD processing: deposits and withdrawals happen in Australian dollars without currency conversion. Most offshore operators run EUR or USD as their base currency, which means depositing AUD via Trustly triggers a 1-3% conversion markup (either by Trustly or the casino’s payment processor), then withdrawing back to AUD hits another conversion layer. Skycrown avoids that double-dip by processing transactions in AUD end-to-end.
The 5,000+ game library aggregates multiple providers, similar scale to PlayAmo. Live casino offering is present but not differentiated. The daily withdrawal limit is AUD $7,500, the highest in this comparison outside of potential VIP tiers at LeoVegas (which are not publicly documented). Weekly limit is $15,000, monthly $45,000. That daily cap is nearly double Jackpot City’s $4,000 baseline, which matters for players who hit a large win and want to cash out quickly without splitting the withdrawal across multiple days. The catch: minimum Trustly deposit is AUD $30, triple the $10 baseline at Malta-licensed competitors. Trustly withdrawal processing is advertised at 1-3 days after casino approval, slower than PlayAmo’s 12-hour or LeoVegas’s 24-hour claims. Realistic end-to-end timeline: 2-5 days first withdrawal.
Skycrown’s 2022 launch means less than three years of operational history as of 2026. The Curaçao license provides baseline legitimacy but lacks the player-protection frameworks of MGA or UKGC. Dispute resolution routes through Curaçao arbitration, which historically resolves slower and with less transparency than Malta’s licensing authority. The native AUD processing is the structural win here — it eliminates hidden currency conversion costs that eat 2-6% of your bankroll across deposit and withdrawal at EUR/USD-based casinos. If you deposit and withdraw frequently in smaller amounts, that conversion saving compounds. If you prioritise withdrawal speed or regulatory credibility, PlayAmo or LeoVegas rank higher.
Spin Casino
Spin Casino is a sister brand to Jackpot City, both operated by Baytree Interactive Ltd under the same MGA and Kahnawake dual licensing. The game library, payment processing, backend infrastructure, bonus structure, and customer support are functionally identical to Jackpot City. The differentiation is cosmetic: Spin Casino’s interface uses a different colour palette and visual design, but the same 500+ Microgaming-heavy game catalogue, the same 24-48 hour Trustly withdrawal processing, the same AUD $10 minimum deposit, and the same AUD $4,000 daily withdrawal baseline.
Some players prefer Spin Casino’s interface over Jackpot City’s slightly dated design. Others find the near-identical offering redundant. The operational advantage of running two brands under one license is that Baytree can segment marketing (Spin Casino skews slightly younger demographic in its branding) without duplicating compliance infrastructure. For the player, it means if Jackpot City’s visual design feels stale, Spin Casino offers the same reliability with a fresh coat of paint. The dual MGA + Kahnawake licensing, 20+ year operational history (Spin launched in the early 2000s, slightly after Jackpot City), and Microgaming progressive access are identical. Trustly implementation is the same payment processor integration Baytree uses across both brands, so withdrawal timelines mirror Jackpot City: 24-48 hours Trustly processing, 48-96 hours end-to-end first withdrawal.
If you already have an account at Jackpot City and want variety without re-doing KYC verification at a new operator, opening a Spin Casino account under the same parent company does not bypass verification — Baytree treats them as separate for compliance purposes. The practical takeaway: Spin Casino and Jackpot City are interchangeable. Pick whichever interface you prefer. The underlying operation is the same.
Royal Panda Casino
Royal Panda Limited launched March 10, 2014, then was acquired by LeoVegas Gaming plc in 2017. When MGM Resorts bought LeoVegas in 2022, Royal Panda came along as part of the corporate family. The brand positioning is “curated casino” — a smaller, quality-focused game library (estimated 1,000-2,000 titles, exact count not disclosed) rather than the 5,000-6,000 aggregated catalogues at LeoVegas or Skycrown. Providers include the major studios (Evolution for live dealer, NetEnt, Microgaming, Play’n GO), but the selection emphasises popular, high-RTP titles over sheer volume.
The key differentiator is transparent bonus terms. Royal Panda’s welcome bonus typically offers 100% match up to AUD $1,000 plus free spins, with wagering requirements in the 30-35x range — lower than the 40-50x some competitors push. The bonus T&Cs are written in plain language with less buried fine-print compared to industry average, which casino.org and other review aggregators have flagged as a player-friendly outlier. That transparency extends to withdrawal terms: the cashier page clearly states processing times, fees (none for Trustly), and limits without requiring a support-ticket inquiry to surface the actual numbers.
Trustly withdrawal processing is 24-48 hours after casino approval, standard for MGA + UKGC operators. Minimum Trustly deposit is AUD $10. Daily withdrawal limit is not publicly disclosed on the main terms page, which is an odd gap given Royal Panda’s otherwise-transparent stance. Customer support reports vary but anecdotal accounts suggest baseline daily limits similar to LeoVegas’s $4,000 tier, with VIP negotiation available for higher-volume players. The MGA + UKGC dual licensing mirrors LeoVegas’s regulatory credibility. The LeoVegas/MGM ownership since 2017/2022 provides corporate backing and financial stability. If you value clear bonus terms and a less-overwhelming game selection over raw speed or the largest library, Royal Panda is the user-friendly pick. Trustly implementation is reliable but not optimised for speed — expect 48-96 hours end-to-end first withdrawal, same as Jackpot City and Spin Casino.
Wild Fortune Casino
Rabidi N.V. operates Wild Fortune under a Malta Gaming Authority license (MGA/B2C/394/2017), launched in 2020. Some sources reference Curaçao licensing as well, suggesting either dual licensing or a license transition at some point in Rabidi’s corporate history. The MGA license is verified and current, placing Wild Fortune in the Tier 1 regulatory category alongside Jackpot City, LeoVegas, and Royal Panda. Rabidi manages multiple casino brands under the same license umbrella, a common structure for European operators.
The aggressive welcome bonus is the headline feature: 225% match up to AUD $7,500 plus 250 free spins with 0x wagering on the spins. That zero-wagering structure on free spins is rare — most operators attach 30-50x playthrough to bonus spins, meaning you must wager winnings 30-50 times before withdrawal. Wild Fortune’s 0x on spins means whatever you win from the 250 spins is withdrawable immediately. The catch is the deposit match itself carries 45x wagering requirements, higher than the 35-40x industry average. That 225% match percentage is also unusually high; typical welcome bonuses cap at 100-150%. The combination of high match percentage and high wagering suggests the bonus is designed to attract large first deposits but with a steep playthrough barrier before the match bonus converts to withdrawable cash.
Game library size is not explicitly disclosed but multi-provider aggregation suggests 2,000-3,000+ titles. Live casino offering is standard. Trustly withdrawal processing is 1-5 days after casino approval, the slowest in this comparison. That 1-5 day range is wide enough to accommodate both fast and slow scenarios, which usually indicates processing speed varies by account verification status, withdrawal amount, and time of week. Minimum Trustly deposit is AUD $30. Daily withdrawal limit is AUD $1,000, the lowest in this comparison — less than a quarter of Skycrown’s $7,500 daily cap. Weekly limit is $5,000, monthly $15,000. For players who hit a $10,000 win, that $1,000 daily cap means splitting the withdrawal across 10 days minimum, or negotiating higher limits through VIP status (which requires account history and is not guaranteed).
Wild Fortune’s MGA licensing provides stronger dispute resolution than Curaçao, but the slow Trustly processing (1-5 days) and low daily withdrawal limit ($1,000) position it at the bottom of this comparison for payout speed and flexibility. The 225% welcome bonus with 0x spins is the draw, but the 45x wagering on the match and the $1,000 daily cap create friction on the back end. Realistic end-to-end withdrawal timeline: 2-7 days first withdrawal, potentially longer if the 1-5 day processing stretches toward the upper bound.
Playfina Casino
Softgenius N.V. launched Playfina in 2022 under Curaçao eGaming license 8048/JAZ2020-13. As a 2022 operator, Playfina has less than three years of operational history, putting it in the same “newer operator” category as Skycrown but without Skycrown’s native AUD processing advantage. The game library is large (multi-provider aggregation, exact count not disclosed), live casino offering is present, and the welcome bonus is 100% up to AUD $6,500 plus 300 free spins — standard structure, middle-of-the-pack terms.
The distinguishing feature is the monthly withdrawal limit: AUD $70,000, the highest in this comparison. Most operators cap monthly withdrawals at $30,000-$45,000; Playfina’s $70,000 monthly ceiling is nearly double. That high monthly cap suggests tolerance for high-volume winners, which is unusual for a newer Curaçao operator. Daily withdrawal limit is AUD $7,000 (competitive with Skycrown’s $7,500), weekly limit is $10,000. The daily-to-weekly ratio is unusual: $7,000 daily but only $10,000 weekly means you can withdraw $7,000 on day one, then just $3,000 more across the next six days before hitting the weekly cap. That structure limits burst withdrawals but allows larger monthly totals if spaced out.
Trustly withdrawal processing is 1-3 days after casino approval, middle-tier speed. Minimum Trustly deposit is AUD $30. Realistic end-to-end withdrawal timeline: 2-5 days first withdrawal. The Curaçao eGaming license is Tier 2 — lower regulatory oversight than MGA or UKGC. Dispute resolution routes through Curaçao arbitration. Softgenius N.V. does not have the multi-decade operational history of Baytree (Jackpot City/Spin) or the corporate backing of LeoVegas/MGM. The high monthly limit ($70,000) is the structural advantage, but it only matters if you’re withdrawing in that volume range. For most recreational players depositing $50-$500 per session, the daily and weekly caps are the binding constraints, and Playfina’s daily $7,000 is competitive but not standout. If you anticipate hitting large wins and cashing out $50,000+ per month, Playfina’s monthly ceiling is the highest. For smaller-scale play, PlayAmo’s faster Trustly processing or LeoVegas’s regulatory credibility rank higher.
How Trustly Works at Australian Casino Sites
Trustly operates as a payment service provider licensed in Sweden, not as a card network or a stored-value wallet. The method moves money directly between your Australian bank account and the casino’s account using one of two technical pathways: open banking APIs where your bank supports them, or direct bank integrations where it does not. Both pathways achieve the same outcome — an authenticated bank-to-bank transfer initiated through Trustly’s infrastructure and settled through the banking system itself — but the technical route depends on which Australian bank you use.
The key structural difference from cards or e-wallets is that Trustly does not hold an intermediate balance. You are not funding a Trustly account, then moving that balance to the casino. The transfer happens in one step, authenticated at your bank’s login page using the credentials and two-factor authentication your bank already requires for online banking. Trustly never receives your bank password or account number in a form it can store. The authentication happens inside your bank’s own environment, with Trustly acting as the initiator and verifier of the transfer rather than as a custodian of your funds.
That bank-mediated authentication model is the security advantage over methods where you input card numbers on various merchant sites. Every card transaction involves sharing your card number, expiry, and CVV with the merchant’s payment processor, which stores those details (tokenized, ideally, but still stored) for future transactions. Trustly transactions are authenticated per-transfer at the bank level, with no standing credential stored at the casino or Trustly’s side. The tradeoff is bank compatibility: not all major Australian banks support Trustly for gambling-related transfers as of 2026, which creates a friction point before you even reach the deposit stage.
The Direct Bank Transfer Model
When you select Trustly at a casino cashier and enter a deposit amount, you are redirected to Trustly’s interface, which presents a list of supported banks. If your Australian bank appears on that list, you select it and are redirected to the bank’s own login page. That login page is hosted by your bank, not by Trustly or the casino, which is why the URL changes to your bank’s domain and why the interface matches your bank’s standard online banking login. You authenticate using the same username, password, and two-factor authentication (SMS code, authenticator app, or hardware token) that you use to log into online banking from your phone or computer.
Once authenticated, your bank presents a summary of the specific transfer Trustly is requesting: the amount, the recipient (the casino’s payment processor), and a confirmation button. You approve or decline that exact transfer. If approved, your bank debits your account, sends confirmation to Trustly, and Trustly notifies the casino. The casino credits your balance instantly — usually within 30-90 seconds of approving the transfer at your bank. The funds have not yet settled through the banking system (settlement takes 1-2 business days on the backend, same as any bank transfer), but the casino receives real-time confirmation from Trustly that the transfer is authorised and will clear, so they credit your account immediately.
If your bank does not support open banking APIs, Trustly uses a direct bank integration instead. The flow looks identical from your side — you still log in at your bank’s page and approve the transfer — but the backend technical route differs. Open banking is the newer, standardized approach; direct integration is the legacy fallback. Both work. The limitation is bank coverage: Trustly’s supported-bank list in Australia is not comprehensive. Some major banks do not appear, which means Trustly is not an option for accounts at those banks. The list updates periodically as Trustly negotiates new bank partnerships, but as of 2026, gaps remain.
Deposit Flow Step-by-Step
The deposit flow takes roughly one to two minutes if your bank login and authentication work smoothly. Friction points appear when your bank is not on Trustly’s list, when you mistype your bank password, when two-factor authentication times out, or when your bank flags the transfer as suspicious and requires additional verification. Those friction points are rare but not zero, and they are harder to troubleshoot than a declined card because the error surfaces at your bank’s side, not at the casino or Trustly layer.
Step one: you navigate to the casino cashier, select Trustly as the deposit method, and enter the amount you want to deposit. The casino’s cashier interface checks that amount against Trustly’s minimum (typically AUD $10-$30) and the casino’s own deposit caps (typically $1,000-$5,000 per transaction). If the amount is within range, you click “Deposit” and are redirected to Trustly’s interface.
Step two: Trustly presents a list of supported Australian banks. You select your bank from that list. If your bank does not appear, Trustly is not available for your account, and you must choose a different payment method at the casino cashier. Assuming your bank is listed, you click it and are redirected to your bank’s login page.
Step three: you log in to your bank using your existing online banking credentials. This step happens on your bank’s domain, not on Trustly’s or the casino’s site. The URL in your browser address bar should match your bank’s standard online banking URL. If it does not, stop and verify you were not redirected to a phishing page. Legitimate Trustly deposits route through your bank’s real login page, with SSL/TLS encryption and your bank’s standard security features active.
Step four: after successful login, your bank displays a transfer authorisation screen showing the exact amount Trustly is requesting to transfer and the recipient (usually the casino’s payment processor name, not “Trustly”). You review that amount, confirm it matches what you entered at the casino cashier, and approve the transfer. Some banks require two-factor authentication at this step (SMS code, authenticator app code, or biometric confirmation). You complete that authentication and finalize the approval.
Step five: your bank debits your account and sends confirmation to Trustly. Trustly notifies the casino. The casino credits your balance. This happens within 30-90 seconds in typical cases. You are redirected back to the casino site with a confirmation message, and the deposited amount appears in your casino account balance. You can start playing immediately.
Authentication and Security
Trustly’s security model relies on your bank’s authentication, not on Trustly storing credentials or the casino handling sensitive financial data. The two-factor authentication (2FA) requirement at your bank login adds a second verification layer beyond your password: even if someone has your bank password, they cannot complete a Trustly transfer without also accessing your phone (for SMS codes), your authenticator app, or your biometric authentication. That 2FA requirement is enforced by your bank, not by Trustly, which means the security standard is whatever your bank applies to all online banking sessions.
Because Trustly does not store your bank credentials, a data breach at Trustly or the casino does not expose your bank password or account details. The transaction is tokenized: Trustly receives a confirmation token from your bank saying “this transfer is authorised,” but the token cannot be reused to initiate further transfers without you logging in again. Every Trustly transaction requires fresh authentication at your bank. That per-transaction authentication is more secure than storing card details, where a breach of the casino’s payment processor can expose card numbers for replay attacks.
The limitation is phishing risk. If you are redirected to a fake bank login page that mimics your bank’s interface, you could input your credentials on a phishing site instead of the real bank page. Legitimate Trustly deposits always redirect to your bank’s official domain, with the correct SSL certificate and URL structure. Check the address bar before entering your password. If the URL looks wrong or the SSL certificate does not match your bank, close the window and contact the casino’s support. Trustly itself does not ask for your bank password; only your bank’s login page does.
Do I need to create a Trustly account to use it?
No. Trustly is a payment processor, not an account-based service like PayPal or Skrill. You do not sign up for Trustly, create a Trustly username, or fund a Trustly balance. When you select Trustly at a casino cashier, you log in directly to your bank and approve the specific transfer. Trustly acts as the bridge between your bank and the casino, verifying the transfer authorisation, but you do not interact with Trustly as a separate account. Every Trustly transaction requires logging in to your bank from scratch. There is no stored Trustly login, no Trustly app to download, no Trustly balance to manage. You use your existing online banking credentials, and Trustly handles the backend communication with the casino.
Is Trustly safe for online casino deposits in Australia?
Trustly is a licensed payment service provider regulated by the Swedish Financial Supervisory Authority, operating since 2008. The payment infrastructure uses 2048-bit encryption, and transactions are authenticated at your bank’s level using the same security standards your bank applies to any online banking session. From a technical and regulatory standpoint, Trustly is legitimate. The risk is not Trustly itself but the offshore casino you are funding. Because no Australian-licensed online casinos exist under the Interactive Gambling Act 2001, every casino accepting Trustly deposits from Australians operates offshore — Curaçao, Malta, Kahnawake. Trustly facilitates the transfer, but once your funds land in the casino’s account, Australian consumer protection ends. Dispute resolution routes through the casino’s offshore regulator, not through an Australian tribunal or the Australian Communications and Media Authority.
Trustly does not control how the casino handles your funds after deposit, whether the casino honours withdrawal requests, or whether the casino operates fairly. A secure payment method moving money into an unregulated or poorly-regulated casino does not make the casino safe. The security of Trustly as a payment processor is separate from the question of whether the casino is trustworthy. Choose casinos with MGA or UKGC licensing (Jackpot City, LeoVegas, Royal Panda) over Curaçao-only operators if regulatory oversight matters. Trustly will move your money to any casino that has integrated the payment method, but it does not vet the casino’s operational integrity.
Trustly Withdrawals: Real Timelines and Limits
Marketing claims of “instant Trustly withdrawals” or “24-hour payouts” measure only one segment of a three-stage process. The full journey from clicking “withdraw” at the casino cashier to seeing funds in your Australian bank account involves the casino’s internal approval period, Trustly’s processing window, and your bank’s incoming transfer credit time. Each stage adds hours or days, and the total rarely matches the headline number the casino advertises.
Understanding where delays occur helps set realistic expectations and diagnose problems when a withdrawal sits pending longer than expected. The friction is usually at the casino approval stage (KYC verification, manual review for large withdrawals, weekends and holidays) rather than at Trustly’s payment processing layer. Trustly itself moves money fast once instructed to do so. The bottleneck is getting the casino to issue that instruction.
The Three-Stage Withdrawal Process
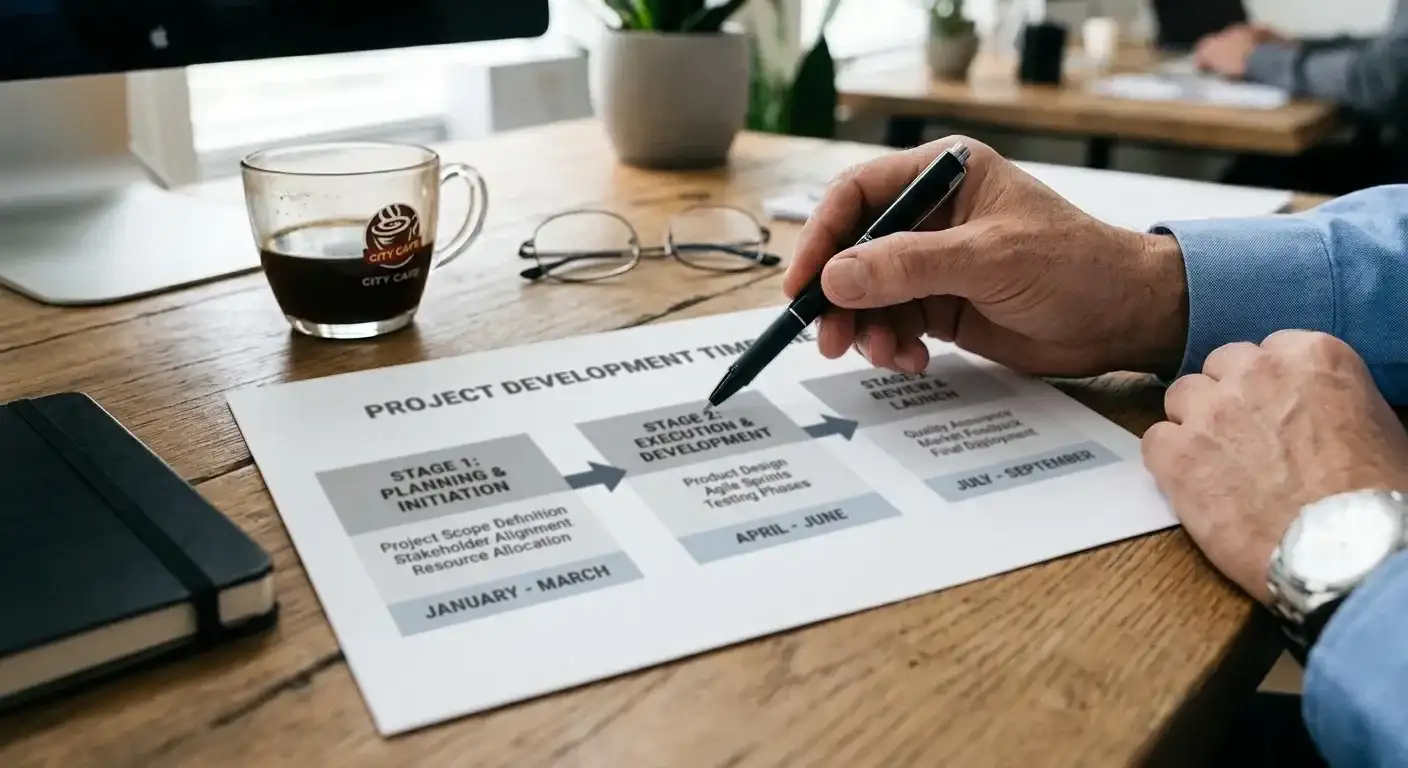
Stage one is the casino’s internal pending period. You request a withdrawal at the cashier, selecting Trustly as the payout method and entering the amount. The casino places that withdrawal request in a pending queue. During this pending period, the casino verifies your account (KYC check if not already completed), checks that you meet wagering requirements if you claimed a bonus, and may flag the withdrawal for manual review if the amount exceeds a threshold or if your account shows unusual activity patterns. This stage takes anywhere from zero hours (if KYC is pre-cleared, no bonus wagering applies, and the withdrawal is routine) to 24 hours or more (if documents are required, if the request lands on a weekend, or if the casino’s finance team is understaffed).
Some casinos allow you to cancel a pending withdrawal during this stage, which is convenient if you change your mind but also creates a psychological friction point — the “reverse withdrawal” temptation where you cancel the payout and gamble the funds instead. That temptation is by design. Longer pending periods correlate with higher reverse-withdrawal rates, which benefits the casino’s retention metrics. Operators with faster Trustly processing (PlayAmo’s 12-hour claim, LeoVegas’s 24-hour window) often have shorter pending periods as well, though exact pending times are not always disclosed in the terms.
Stage two is Trustly’s processing window. Once the casino approves the withdrawal and instructs Trustly to initiate the bank transfer, Trustly processes the payout. This is the stage the casino’s “24-hour Trustly withdrawal” marketing refers to. PlayAmo advertises 12 hours, LeoVegas and the MGA operators typically claim 24 hours, and slower operators like Wild Fortune state 1-5 days. In practice, Trustly processing is often faster than the advertised maximum — 12-hour claims sometimes complete in 6 hours, 24-hour windows sometimes close in 12 — but the advertised figure is the upper bound you should plan around. Trustly processes withdrawals by initiating a bank transfer from the casino’s account to your Australian bank account, using the same bank-authentication infrastructure as deposits but in reverse (the casino authorises the outbound transfer, Trustly verifies and executes it).
Stage three is your bank’s incoming transfer credit time. After Trustly initiates the transfer, your Australian bank receives the incoming funds and credits your account. This stage is outside both the casino’s and Trustly’s control. Some Australian banks credit incoming transfers instantly or within a few hours. Others batch-process incoming transfers once or twice per day, which can add 12-24 hours. In rare cases, a bank may hold an incoming transfer for additional verification if the amount is large or if the source (an offshore casino payment processor) triggers their fraud-detection algorithms. That hold can extend to 48 hours. The bank does not notify you during this hold period; from your perspective, the withdrawal is simply delayed with no clear explanation.
Add those three stages together for the realistic end-to-end timeline. Best case: casino approves instantly (0 hours) + Trustly processes in 6 hours + bank credits in 2 hours = 8 hours total. Typical case for established accounts: casino approves in 6-12 hours + Trustly processes in 12-24 hours + bank credits in 12-24 hours = 30-60 hours total (1.25 to 2.5 days). Worst case for first withdrawals: casino holds for KYC documents and manual review (24 hours) + Trustly processes at the upper bound (24-48 hours depending on operator) + bank holds for verification (24-48 hours) = 72-120 hours total (3 to 5 days). A “24-hour Trustly withdrawal” marketed by the casino can realistically take 72 hours end-to-end on a first payout.
Why “24-Hour Trustly Withdrawals” Can Take 72 Hours
The gap between marketing and reality is not fraud; it is selective measurement. When a casino advertises “24-hour Trustly withdrawals,” they are measuring only stage two (Trustly’s processing window) and excluding stage one (casino pending) and stage three (bank credit time). That 24-hour figure is technically accurate for what Trustly does, but it is not the full story of how long you wait.
Casino pending periods are the most variable stage. If your account has completed KYC verification (uploaded ID, proof of address, and had those documents approved) and if you have no active bonus wagering requirements, the casino can approve your withdrawal in minutes. Many casinos batch-process withdrawal approvals once or twice per day rather than continuously, so even a pre-cleared account might wait 6-12 hours if the request lands between approval runs. On weekends and holidays, some casinos reduce finance staff, which extends pending periods to 24-48 hours. Large withdrawals (several thousand dollars or more) often trigger manual review regardless of account status, adding another 12-24 hours.
First-time withdrawals almost always require KYC verification if you have not already completed it. The casino emails a request for documents (photo ID, a recent utility bill or bank statement showing your address, sometimes a selfie holding your ID, sometimes proof of the payment method used for deposit). You upload those documents through the cashier or a secure portal. The casino reviews them, which takes 12-48 hours depending on the operator’s compliance-team staffing. If a document is rejected (blurry photo, expired ID, address mismatch), you must resubmit and wait for another review cycle. That KYC loop can extend a first withdrawal to 3-5 days before the casino even approves the payout and hands it to Trustly.
Bank credit time is usually the smallest delay (0-24 hours for most Australian banks) but occasionally stretches to 48 hours if your bank flags the incoming transfer. Trustly transactions from offshore casinos originate from payment processors in Malta, Curaçao, Cyprus, or other jurisdictions, which some Australian banks treat as higher-risk sources. The bank may hold the transfer while they verify it is not a fraudulent deposit. You cannot speed up this stage. Calling your bank might clarify why the hold exists but rarely accelerates the credit.
The lesson is not to distrust casino marketing but to add the unstated stages to the advertised number. A casino advertising 24-hour Trustly processing is telling the truth about Trustly’s part, but your realistic wait is 24 hours (Trustly) + 12 hours (casino pending, best case) + 12 hours (bank credit, typical) = 48 hours minimum, with 72-96 hours common on first withdrawals. Operators advertising 12-hour Trustly processing (PlayAmo) shave 12 hours off that total, landing closer to 36-48 hours end-to-end. Operators advertising 1-5 day Trustly processing (Wild Fortune) stretch to 2-7 days end-to-end.
Withdrawal Limits by Operator
Daily, weekly, and monthly withdrawal limits vary by operator and sometimes by account status (VIP players negotiate higher limits). The daily limit is the binding constraint for most players: it caps how much you can withdraw in a single 24-hour period, regardless of how large your balance is. If you win $20,000 and the daily limit is $4,000, you split the withdrawal across five days minimum, or contact support to request a limit increase (which may or may not be granted).
PlayAmo’s daily limit is AUD $5,000 with a weekly cap around $10,000. That daily figure is competitive but the weekly cap creates a secondary constraint: you can withdraw $5,000 on day one, then $5,000 more across the next six days before hitting the weekly limit. For a $15,000 win, you withdraw $5,000 immediately, then wait a week, then withdraw the next $5,000, then wait another week for the final $5,000. Weekly limits reset on a fixed schedule (often Monday 00:00 UTC), not rolling seven-day windows, which affects timing.
LeoVegas and Jackpot City both set the baseline daily limit at AUD $4,000, with higher limits available for VIP accounts (exact VIP thresholds not publicly disclosed). Royal Panda does not publish daily limits on the main terms page but anecdotal reports suggest similar $4,000 baseline. Spin Casino mirrors Jackpot City at $4,000 daily since both run on Baytree’s infrastructure.
Skycrown offers the highest disclosed daily limit at AUD $7,500, with weekly $15,000 and monthly $45,000 caps. That $7,500 daily figure is nearly double the $4,000 baseline at MGA operators, which matters for large wins. A $30,000 payout splits across four days at Skycrown ($7,500 × 4) versus eight days at Jackpot City ($4,000 × 7, then $2,000 on day eight). The time-to-cashout difference compounds: four days at Skycrown means four separate pending periods, four Trustly processing windows, four bank credit cycles. Eight days at Jackpot City doubles that friction.
Playfina’s daily limit is AUD $7,000 (competitive with Skycrown), weekly $10,000 (lower than Skycrown’s $15,000), but monthly $70,000 (the highest in this comparison). That structure favours steady cashouts over burst withdrawals. Wild Fortune’s daily limit is AUD $1,000, the lowest by a wide margin. A $10,000 win requires ten daily withdrawals, each with its own pending period and processing cycle. The $1,000 daily cap makes Wild Fortune impractical for anything beyond small wins, despite the MGA licensing and the aggressive welcome bonus.
How long does a Trustly withdrawal take from an Australian casino?
Between 12 and 120 hours (half a day to five days) depending on three factors: the operator’s Trustly processing speed, whether your account has completed KYC verification, and your bank’s incoming transfer handling. PlayAmo processes Trustly withdrawals in roughly 12 hours after approval, LeoVegas and the MGA operators take 24-48 hours, and slower operators take 1-5 days. Add the casino’s pending period (0-24 hours, longer on first withdrawals requiring KYC documents) and your bank’s credit time (0-48 hours, typically 12-24). Realistic total: 36-60 hours for established accounts at fast operators, 48-96 hours at standard operators, 72-120 hours on first withdrawals or at slow operators. “Instant” Trustly withdrawals do not exist in practice; the fastest real-world timeline is around 12-24 hours end-to-end under ideal conditions.
Can I withdraw to a different bank account than I deposited from?
Most casinos require Trustly withdrawals to return to the same bank account used for deposit. That same-account requirement is an anti-money-laundering control: it prevents using the casino as a pass-through to move funds between accounts. If you deposited from Commonwealth Bank account A and later want to withdraw to Westpac account B, the casino will likely reject the withdrawal and ask you to provide the original deposit account. Switching accounts between deposit and withdrawal is possible at some operators if you contact support, upload verification documents for the new account (bank statement proving ownership), and provide a reason for the switch (e.g., you closed the original account). That process adds 24-48 hours to the withdrawal timeline and is not guaranteed. The simplest path is to use one bank account consistently for both deposits and withdrawals at a given casino.
Fees, Currency Conversion, and Hidden Costs
Trustly itself does not charge players a per-transaction fee for deposits or withdrawals. The business model positions Trustly as a merchant-services provider: the casino pays Trustly a percentage of each transaction, and that cost is not passed to the player as a line-item fee. In typical scenarios, you deposit $100 via Trustly and $100 appears in your casino balance. You withdraw $100 and $100 lands in your bank account. No $2 fee, no 1% deduction, no surcharge listed on the transaction.
That fee-free structure is real in the narrow sense that Trustly itself charges you nothing, but it does not mean the full transaction is cost-free. Costs can appear at three points: the casino may impose a withdrawal fee (rare but not nonexistent), your bank may charge for outgoing or incoming transfers (uncommon for domestic Australian bank accounts but possible depending on account type and bank policy), and currency conversion adds a hidden percentage markup if the casino’s base currency does not match your deposit currency.
Currency conversion is the silent cost that most players miss until they compare the amount debited from their bank statement to the amount credited in their casino account. If you deposit AUD $100 into a casino that operates in EUR, Trustly (or the casino’s payment processor) converts your $100 AUD to approximately €60 EUR at the prevailing exchange rate plus a conversion markup. That markup is typically 1-3% above the mid-market exchange rate, meaning you receive €58.50-€59.50 instead of €60. When you later withdraw €60 back to AUD, the reverse conversion applies, and €60 becomes roughly AUD $97-$98 after the markup. You have lost 2-3% of your bankroll to conversion on the round trip, even though no “fee” was listed.
Casinos that process transactions in AUD eliminate that conversion cost. Skycrown is the only operator in this comparison that explicitly advertises native AUD processing: deposits and withdrawals happen in Australian dollars without touching a EUR or USD intermediary. That native-currency advantage saves 2-3% per deposit-withdrawal cycle, which compounds if you deposit and cash out multiple times per month. A player depositing $500 ten times per month at a EUR-based casino loses roughly $100-$150 per month to conversion markups ($500 × 10 deposits × 2% = $100 minimum). At an AUD-native casino, that $100-$150 stays in your bankroll.
Most offshore casinos operate in EUR or USD as their base currency because they serve multiple international markets and consolidating to one currency simplifies accounting. The tradeoff for Australian players is the conversion markup. Some casinos allow you to choose your account currency at signup (EUR, USD, AUD, GBP), but “choosing AUD” does not always eliminate conversion if the casino’s backend still processes in EUR and simply displays your balance in AUD equivalent. True native AUD processing means the casino’s payment processor holds your funds in AUD from deposit to withdrawal without converting to EUR in between. Skycrown’s structure does this; most others do not.
Are there fees for using Trustly at online casinos?
Trustly does not charge players a fee for deposits or withdrawals. The casino pays Trustly’s transaction fee as part of the merchant-services agreement, so from the player’s perspective, Trustly transactions are fee-free in the majority of cases. Two exceptions exist: some casinos impose their own withdrawal fee (a flat AUD $5-$10 charge or a percentage of the withdrawal amount) regardless of payment method, and some Australian banks charge account holders for outgoing transfers or incoming deposits depending on account type. Check the casino’s withdrawal terms before requesting a payout, and check your bank’s fee schedule if you are using a business account or a specialized account type rather than a standard everyday transaction account. Standard Australian consumer bank accounts rarely charge for incoming domestic transfers, but outgoing transfers to international recipients (which an offshore casino payment processor may be classified as) can trigger fees at some banks.
Currency conversion is the larger hidden cost. If the casino’s base currency is EUR or USD and you deposit in AUD, the conversion markup (1-3% above mid-market exchange rate) applies on both deposit and withdrawal. That markup is not listed as a fee but functions as one. For a player depositing and withdrawing AUD $1,000 per month at a EUR-based casino, the conversion cost is roughly AUD $20-$60 per month. Over a year, that is $240-$720 lost to currency conversion. Using a casino that processes in AUD (Skycrown) eliminates that ongoing cost.
Trustly for Pokies: The Australian Angle
Pokies — the Australian term for slot machines and video slots — account for the majority of online casino play in the Australian market. Trustly’s instant deposit capability fits the behavioural pattern of pokies sessions: smaller, repeated top-ups rather than single large bankrolls. A player might deposit $50 to fund a session, play through that balance in 20-30 minutes, then decide whether to top up another $50 or walk away. Trustly’s 30-90 second deposit flow supports that session-based play without the friction of waiting for card authorisation or pre-loading an e-wallet days in advance.
The search volume around “trustly pokies” and “instant withdrawal pokies trustly” reflects two priorities specific to the Australian market. First, pokies are the dominant game type, so payment-method searches are framed around pokies rather than generic “casino” terms. Second, Australian players prioritise withdrawal speed more than most markets, likely due to the offshore-operator structure: faster withdrawals reduce the window during which the casino could impose friction, reverse a payout, or delay processing. Trustly’s 12-48 hour processing window (depending on operator) is faster than credit card withdrawals (3-5 business days) but slower than cryptocurrency (1 hour after casino approval). That middle-ground speed positions Trustly as the practical compromise for players who want faster payouts than cards but do not want to deal with crypto wallets and exchange-rate volatility.
All Trustly-accepting operators in this comparison offer large pokies libraries. Jackpot City and Spin Casino emphasise Microgaming pokies (500+ titles including progressive jackpots like Mega Moolah). PlayAmo, Skycrown, and Playfina aggregate 3,000-5,000+ pokies from multiple providers (Microgaming, NetEnt, Pragmatic Play, Play’n GO, BGaming). LeoVegas’s 6,000+ game library includes the broadest pokies selection in this comparison. The payment method does not affect which pokies are available; Trustly processes deposits and withdrawals the same way regardless of whether you play pokies, table games, or live dealer. The “Trustly pokies” search cluster is behavioural labelling, not a technical distinction.
The practical consideration is minimum deposit and withdrawal limits. Trustly’s typical AUD $10-$30 minimum deposit aligns with casual pokies sessions. A player can fund a $10 or $20 session without committing to a $100 minimum. Withdrawal minimums are typically $20-$50, which means small wins ($30-$80) are withdrawable without needing to build a larger balance first. That low-friction deposit and withdrawal structure supports the stop-and-start play pattern common in pokies sessions, where a player might cash out a $60 win rather than reinvesting it in another session.
Trustly vs. Other Payment Methods
Trustly occupies a middle ground between traditional banking methods (cards, bank transfers) and newer alternatives (e-wallets, cryptocurrency). The table below compares Trustly to the main alternatives available at Australian-facing offshore casinos, focusing on metrics that affect practical usability: speed, cost, anonymity, and bank compatibility within Australia.
| Payment Method | Deposit Speed | Withdrawal Speed | Typical Fees | Anonymity | Bank Compatibility (AU) |
|---|---|---|---|---|---|
| Trustly | Instant | 12-48 hours | None (player), 1-3% currency conversion if applicable | Low (bank statement shows transaction) | Limited (not all major banks support) |
| Credit/Debit Cards | Instant | 3-5 business days | 2-5% cash advance fee common | Low (statement shows transaction) | High (universal) |
| E-Wallets (Skrill, Neteller) | Instant | 12-24 hours | 1-3% withdrawal fee typical | Medium (statement shows e-wallet transfer, not casino) | High (universal, funded via bank or card) |
| Cryptocurrency (Bitcoin, Ethereum) | 10-60 minutes | Under 1 hour (after casino approval) | Network fees (variable, $1-$20) | High (pseudonymous) | High (universal via exchange) |
| PayID | Instant | Instant-24 hours | None | Low (statement shows transaction) | High (Australian banks only) |
Credit and debit cards remain the most universally accepted method, but Australian banks increasingly treat casino deposits as cash advances, which triggers immediate interest accrual (often 20%+ APR) and a 2-5% upfront fee. That cash-advance treatment makes cards expensive for regular deposits. Withdrawals back to cards are slow (3-5 business days) and some Australian banks block incoming gambling-related credits entirely, requiring you to choose a different withdrawal method even if you deposited by card. Cards are convenient but costly.
E-wallets like Skrill and Neteller offer similar deposit speed to Trustly (instant) and slightly faster withdrawals (12-24 hours typical). The advantage is that your bank statement shows only the e-wallet transfer, not the casino, which provides a layer of transactional privacy. The disadvantage is that you must create and maintain a separate e-wallet account, fund it in advance (usually via bank transfer or card, which adds a preliminary step), and pay 1-3% withdrawal fees when moving funds from the e-wallet back to your bank. Trustly eliminates the e-wallet intermediary, moving money directly between your bank and the casino, but at the cost of lower transactional privacy (your bank statement will show the casino payment processor’s name).
Cryptocurrency (Bitcoin, Ethereum, Litecoin) is the fastest withdrawal method: often under one hour after casino approval, compared to Trustly’s 12-48 hours. Crypto also offers the highest anonymity — transactions are pseudonymous, tied to wallet addresses rather than your legal name and bank account. The tradeoff is complexity (you must use a cryptocurrency exchange to convert AUD to crypto before depositing, then convert crypto back to AUD after withdrawing) and exchange-rate volatility (the value of your crypto balance fluctuates between deposit and withdrawal). Network transaction fees for Bitcoin and Ethereum can spike during high-traffic periods, sometimes costing $10-$20 per transaction. For players comfortable with crypto infrastructure, it is the fastest and most anonymous option. For players who want the simplicity of bank-based payments, Trustly is faster and easier.
PayID is a newer payment method specific to Australian banks, offering instant deposits and fast withdrawals (instant to 24 hours). The advantage is that PayID is Australia-native, so no currency conversion and no offshore payment processor intermediary. The limitation is availability: not all offshore casinos support PayID, and those that do often impose lower transaction limits than Trustly. PayID is also tied to your Australian bank account the same way Trustly is, so transactional privacy is low. For casinos that support both Trustly and PayID, PayID is often the faster and cheaper option for Australian players. For casinos that only support Trustly (or support PayID with restrictive limits), Trustly is the practical fallback.
What’s the difference between Trustly and PayID for casino deposits?
Both are direct bank transfer methods, but PayID is Australia-specific and Trustly is a European payment processor operating internationally. PayID deposits and withdrawals are often instant or near-instant (under 24 hours) because they route through Australia’s New Payments Platform (NPP), a real-time banking infrastructure that Australian banks built domestically. Trustly routes through international banking rails and open banking APIs, which adds 12-48 hours to withdrawals. PayID is faster for the subset of casinos that support it, but offshore casino adoption of PayID is lower than Trustly adoption because Trustly serves a global market and PayID is Australia-only. If your casino offers both, PayID is usually the better choice for speed. If your casino only offers Trustly, or if PayID limits are too low for your deposit size, Trustly is the alternative.
Is Trustly faster than cryptocurrency for casino withdrawals?
No. Cryptocurrency withdrawals process in under one hour after casino approval in typical cases, compared to Trustly’s 12-48 hours. The speed advantage of crypto is substantial: a Bitcoin or Ethereum withdrawal approved by the casino at 10:00 AM often lands in your wallet by 11:00 AM the same day. Trustly withdrawals approved at 10:00 AM land in your bank account 12-48 hours later, typically the next business day at earliest. The tradeoff is complexity and cost. Crypto requires setting up a wallet, using an exchange to convert AUD to crypto before depositing, and converting crypto back to AUD after withdrawing. Exchange fees and network transaction fees add up. Trustly deposits and withdrawals use your existing bank account with no intermediate conversion, making it simpler but slower. If speed is the only priority and you are comfortable with crypto infrastructure, crypto beats Trustly. If you want the simplicity of bank-based payments, Trustly is faster than cards (3-5 days) and e-wallets (12-24 hours) but slower than crypto.
Trustly and Australian Gambling Laws
No Australian-licensed online casinos exist. That sentence is the foundation of every discussion about offshore operators, payment methods, and legal risk for Australian players in 2026. The Interactive Gambling Act 2001 (IGA) prohibits companies from offering “real-money” online casino services — slots, table games, in-play sports betting — to persons physically located in Australia. The prohibition targets operators, not players. It is illegal to offer these services to Australians; it is not illegal to use these services as an Australian resident.
Every casino accepting Trustly deposits from Australian players operates under an offshore license — Curaçao eGaming, Malta Gaming Authority, Kahnawake Gaming Commission, or others — and is based outside Australian jurisdiction. These operators are not subject to Australian regulatory oversight, Australian consumer protection laws, or Australian dispute resolution frameworks. Trustly facilitates the payment between your Australian bank and the offshore casino’s account, but Trustly itself is not the gambling operator and does not circumvent Australian law. Trustly is a licensed payment service provider operating legally in Australia; it processes transactions for various merchants, including offshore casinos. The legal ambiguity sits with the casino, not the payment method.
The Interactive Gambling Act 2001
The IGA’s Section 15 makes it an offence for a person to provide an “interactive gambling service” to customers in Australia. An interactive gambling service includes online casino games (pokies, table games, live dealer) and in-play sports betting. The penalty for breaching Section 15 is directed at the operator, not the player. Australian residents are not prosecuted for using offshore casino sites. The Australian Communications and Media Authority (ACMA) enforces the IGA by blocking offshore casino websites (ISP-level DNS blocks) and pressuring payment processors and financial institutions to decline gambling-related transactions.
In practice, ACMA enforcement focuses on high-profile operators and payment channels with significant market share. Thousands of offshore casino sites continue to accept Australian players as of 2026, operating openly and advertising through Australian-facing affiliate sites, comparison portals, and search engines. ACMA blocks websites periodically, but operators respond by registering new domains and updating DNS records. The block-and-reopen cycle is ongoing. Payment blocking is more effective: Australian banks and credit card networks have tightened policies around gambling-related transactions, declining some deposits and withdrawals to offshore operators. That payment friction is where most Australian players encounter enforcement, not through legal action against individuals.
What It Means for Players Using Trustly
From a legal standpoint, Australian residents using Trustly to deposit at offshore casinos are not breaking the law. The IGA targets operators, and no provision criminalizes the act of placing a bet or funding an account. From a practical standpoint, the offshore structure means you lose Australian consumer protection. If an offshore casino refuses to honour a withdrawal, imposes unfair terms, or operates rigged games, your recourse is limited to the casino’s licensing jurisdiction. Malta Gaming Authority and UK Gambling Commission licenses provide formal dispute resolution paths (file a complaint with the regulator, who investigates and can sanction or revoke the operator’s license). Curaçao eGaming licenses provide baseline oversight but historically resolve disputes slower and with less transparency. Casinos with no license or unverifiable licenses offer no dispute resolution beyond direct negotiation with the operator.
Trustly transactions route through your Australian bank, so they appear on your bank statement. The statement line typically shows the casino’s payment processor name (often a generic corporate entity like “Tech Solutions Ltd” or “Global Services Group”) rather than the casino brand, but the transaction is traceable. If your bank has a policy against gambling-related transactions, they may block the outgoing transfer at the point of deposit or freeze the incoming transfer at withdrawal. That bank-level blocking is more common with credit cards than with direct bank transfers, but it is not zero. Some Australian banks allow gambling transactions without restriction; others quietly decline them without explanation. Trustly cannot override your bank’s policy. If your bank blocks Trustly deposits to casinos, you must use a different payment method or a different bank account.
The risk for Australian players is not legal prosecution (which has not happened to individual players under the IGA as of 2026) but financial: depositing into an offshore casino with weak or no licensing, then facing refused withdrawals or unfair terms with no effective recourse. That risk exists regardless of payment method. Trustly is a secure way to move money, but it does not make an untrustworthy casino trustworthy. Choose casinos with MGA or UKGC licensing (Jackpot City, LeoVegas, Royal Panda, Wild Fortune) over Curaçao-only operators (PlayAmo, Skycrown, Playfina) if dispute resolution matters. The regulatory tier of the casino’s license affects your practical protection more than the payment method you use to fund it.
Offshore Licensing and Player Protection
Offshore licenses are not equal. Malta Gaming Authority and UK Gambling Commission licenses enforce strict operational standards: game fairness (RNG testing and certification), financial solvency (segregated player funds), advertising standards, responsible gambling tools, and transparent dispute resolution. Operators licensed by MGA or UKGC undergo regular audits, submit financial reports, and face penalties (fines, license suspension, revocation) for breaching regulations. A complaint filed with MGA or UKGC against a licensed operator triggers a formal investigation, and the regulator can compel the operator to honour payouts or correct unfair practices.
Curaçao eGaming licenses provide baseline legitimacy (the operator is a registered legal entity, game outcomes are tested for randomness, player data is encrypted) but lack the strict oversight and transparent dispute resolution of MGA or UKGC. Curaçao does not publish detailed audit reports, financial solvency requirements are less stringent, and dispute resolution through Curaçao arbitration is slower and less predictable. That lower regulatory tier does not make Curaçao operators inherently fraudulent, but it increases the risk of unresolved disputes. If an MGA-licensed casino refuses a withdrawal, you file a complaint with MGA and the regulator investigates. If a Curaçao-licensed casino refuses a withdrawal, you file a complaint with Curaçao eGaming and outcomes vary. Some complaints resolve in the player’s favour, others drag on without resolution.
Kahnawake Gaming Commission licenses (held by Jackpot City and Spin Casino alongside their MGA licenses) sit between MGA and Curaçao in regulatory rigor. Kahnawake has a longer operational history than Curaçao eGaming and publishes more transparent licensing standards, but it lacks the enforcement mechanisms and player-fund protections of MGA or UKGC. Operators with dual licensing (MGA + Kahnawake, or MGA + UKGC) offer redundancy: if one regulator’s dispute process stalls, you can escalate through the other.
The practical takeaway is that Trustly moves money efficiently, but the casino’s license determines what happens to that money after it lands in the casino’s account. A fast, secure payment method funding a poorly-regulated casino is still high-risk. Prioritise casinos with MGA or UKGC licenses (Jackpot City, Spin Casino, LeoVegas, Royal Panda, Wild Fortune) if regulatory credibility and dispute resolution matter. Accept Curaçao licenses (PlayAmo, Skycrown, Playfina) only if you value other factors (faster withdrawals, higher limits, native AUD processing) above regulatory oversight.
Can I use Trustly at Australian-licensed casinos?
No Australian-licensed online casinos exist under the Interactive Gambling Act 2001. The IGA prohibits offering online casino games to Australian residents, which means no domestic licensing framework exists for online casinos. The only licensed interactive gambling services in Australia are sports betting and racing, which operate under state and territory licenses (not Commonwealth) and are listed on ACMA’s register of licensed interactive gambling providers. That register does not include any online casinos because the IGA forbids them. Every casino accepting Trustly deposits from Australians is an offshore-licensed operator (Curaçao, Malta, Kahnawake) based outside Australian jurisdiction. Trustly is a payment method used at offshore casinos; it is not available at Australian-licensed services because those services do not include online casinos.
Do Australian banks block Trustly casino transactions?
Some Australian banks block or restrict gambling-related transactions, but policies vary by bank and are not publicly disclosed in detail. Trustly transactions route through the same banking infrastructure as any direct bank transfer, so if your bank allows online gambling payments, Trustly will work. If your bank blocks gambling transactions, Trustly will fail at the point of deposit (your bank declines the outgoing transfer) or at withdrawal (your bank holds or declines the incoming transfer). Credit card blocks are more common than direct bank transfer blocks because card networks (Visa, Mastercard) have stricter gambling-transaction policies than the banking system itself. That said, some of Australia’s major banks have tightened policies on all gambling-related transfers in recent years, affecting Trustly along with cards and e-wallets. You will not know whether your bank blocks Trustly casino deposits until you attempt one. If the deposit fails and the casino cashier returns an error, contact your bank to confirm whether they declined the transaction. If they did, you must use a different payment method or a different bank account at a bank with more permissive policies.
Bonuses and Promotions with Trustly Deposits
Most offshore casinos accept Trustly deposits for welcome bonus eligibility without restrictions. The welcome bonus structure at operators in this comparison follows standard industry patterns: a percentage match on your first deposit (100-225%) up to a maximum amount (AUD $1,000-$7,500), plus free spins on selected pokies, with wagering requirements (30-50x) before you can withdraw bonus funds. Trustly deposits count toward bonus activation the same way card or e-wallet deposits do. There is no “Trustly-specific bonus” that offers better terms, and no penalty for using Trustly instead of another method.
The practical consideration is minimum deposit thresholds for bonus activation. Welcome bonuses typically require a minimum deposit of AUD $10-$30 to trigger the match and free spins. Trustly’s minimum deposit at most operators is $10-$30, which aligns with those bonus thresholds. You do not need to deposit more than the minimum to claim the welcome bonus, though depositing more increases the absolute bonus amount up to the stated maximum. A 100% match up to $1,000 means depositing $50 gets you $50 bonus, depositing $500 gets you $500 bonus, and depositing $1,000 or more gets you the $1,000 maximum bonus. Trustly’s instant deposit speed means you see the bonus credited to your account within seconds of approving the transfer at your bank.
Wagering requirements are the binding constraint on bonus value. A 35x wagering requirement on a $500 bonus means you must wager $17,500 ($500 × 35) on eligible games before the bonus converts to withdrawable cash. Pokies typically contribute 100% toward wagering (every $1 wagered counts as $1 toward the requirement), while table games contribute 0-20% (blackjack and roulette bets count minimally or not at all). Game weighting affects how quickly you clear the wagering requirement. A player who only plays pokies clears 35x faster than a player who splits time between pokies and blackjack.
Some casinos impose maximum bet limits while bonus wagering is active (e.g., no single bet above $5 AUD while clearing wagering requirements). Breaching that limit can void the bonus and any winnings derived from it. Bonus terms also typically cap the maximum withdrawable amount from free-spin winnings (e.g., free spins can generate up to $100 in withdrawable winnings regardless of how much you actually win). Those caps and restrictions are not Trustly-specific; they apply to all deposit methods. Read the bonus terms before claiming, because breaching a term (intentionally or by accident) can forfeit the bonus and your balance.
Wild Fortune’s 225% match with 0x wagering on free spins is the most aggressive welcome offer in this comparison, but the 45x wagering on the match bonus itself is steeper than competitors’ 35-40x. Royal Panda’s transparent bonus terms (lower wagering, clearer T&Cs) make it easier to understand what you are agreeing to, though the absolute bonus amount is smaller ($1,000 max) than Wild Fortune’s $7,500 or Playfina’s $6,500. Jackpot City and Spin Casino offer mid-tier bonuses ($1,600 max, 35x wagering) with straightforward terms. PlayAmo, LeoVegas, Skycrown, and Playfina all offer 100% matches in the $5,000-$7,500 range with 35-45x wagering.
The calculation that matters is not the headline bonus percentage but the effective value after wagering. A $1,000 bonus with 35x wagering requires $35,000 in bets to convert to cash. At a typical pokies RTP of 96%, you lose roughly 4% of total wagers to the house edge, which is $1,400 lost on $35,000 wagered. You started with a $1,000 bonus, lost $1,400 to the house edge while clearing wagering, and end up $400 in the hole before accounting for variance. That calculation shows why large bonuses with high wagering are not “free money” — they are a mechanism to generate betting volume, and the house edge ensures the casino profits on aggregate even after paying out the bonus.
Some players skip bonuses entirely to avoid wagering requirements. Depositing without claiming a bonus means your funds are immediately withdrawable (after meeting any table-game or minimum-wager anti-abuse rules the casino imposes, which are typically minimal). If you plan to deposit $100, play through it, and cash out any winnings within a few hours, claiming a bonus that locks your deposit into 35x wagering is counterproductive. If you plan to play through several hundred dollars over multiple sessions anyway, the bonus gives you extra starting balance at the cost of needing to wager more before withdrawal. Neither approach is wrong; it depends on your play style and risk tolerance.
Common Problems and How to Fix Them
Trustly deposits and withdrawals fail or stall for predictable reasons. Understanding the most common failure modes helps you diagnose and resolve problems faster than contacting support and waiting for a response. The four primary failure points are bank compatibility, authentication errors, KYC verification delays, and same-account withdrawal restrictions. Each has a specific fix.
Bank Not Listed in Trustly
If your Australian bank does not appear in Trustly’s supported-bank list at the casino cashier, Trustly is not available for your account. Trustly’s bank coverage in Australia is not comprehensive; some major banks and most smaller regional banks are not supported. The reason is that Trustly must negotiate individual integration agreements with each bank or rely on that bank supporting open banking APIs. If your bank has not signed an agreement with Trustly and does not participate in Australia’s open banking framework, Trustly cannot process transactions for that account.
The fix is to use a different payment method (PayID if the casino supports it, e-wallets like Skrill or Neteller, cryptocurrency, or cards if you accept the cash-advance fee), or open an account at a bank that Trustly supports and fund casino deposits from that account. The second option is impractical for most players — opening a bank account to access a specific payment method is excessive. The first option (choosing a different payment method) is the realistic path. If Trustly is the only deposit method you want to use and the casino does not support your bank, you must choose a different casino or accept that Trustly is not viable for your situation.
Deposit Failed After Authentication
If you authenticate at your bank, approve the transfer, and the deposit still fails, the failure occurred at your bank’s side (they declined the outgoing transfer after you approved it) or at the casino’s payment processor side (they declined the incoming transfer). Bank-side failures are more common. Reasons include: your account has insufficient funds (the displayed balance does not account for pending debits or holds), your account has a daily transfer limit that the deposit exceeds, your bank flagged the transaction as suspicious (gambling-related transfers to offshore merchants trigger fraud-detection algorithms at some banks), or your bank has a blanket policy against gambling transactions and declined it on that basis.
Check your bank account balance and recent transactions to confirm funds were not debited. If the transfer did not leave your account, the failure was at authorisation stage and you can retry. If funds were debited but did not appear in your casino balance within 5-10 minutes, contact the casino’s support immediately with your transaction ID (Trustly provides a transaction reference number after you approve the transfer at your bank). The casino can trace the deposit through their payment processor and confirm whether it arrived. If it arrived on the casino’s side but was not credited to your account, they credit it manually. If it did not arrive, Trustly investigates where the transfer stalled and initiates a refund, which takes 3-5 business days to return to your bank account.
Do not retry a failed deposit multiple times in quick succession. If the failure is at your bank’s side, retrying will fail again and may trigger additional fraud alerts that lock your account. Contact casino support after the first failure, provide the transaction reference, and let them investigate before attempting another deposit.
Withdrawal Delayed or Rejected
If your withdrawal request sits in pending status longer than the casino’s stated processing time, or if it is rejected outright, the reason is almost always KYC verification. First-time withdrawals require identity verification: you upload a government-issued photo ID (driver’s license, passport), proof of address (utility bill, bank statement dated within the last three months showing your name and residential address), and sometimes proof of the payment method (a screenshot of your online banking showing your account number and name, or a photo of your card with the middle digits obscured). The casino reviews these documents, which takes 12-48 hours. If a document is rejected (blurry photo, expired ID, address on the ID does not match address on the utility bill), you must resubmit and wait for another review cycle.
Some casinos also require source-of-funds verification for large withdrawals (several thousand dollars). They ask for payslips, tax returns, bank statements showing income, or other proof that the funds you deposited came from legitimate sources. That verification is an anti-money-laundering requirement, and refusing to provide it results in the casino freezing your account and withholding withdrawals. The threshold for source-of-funds checks varies by operator and is not publicly disclosed, but withdrawals above $5,000-$10,000 in a short period commonly trigger the requirement.
The fix is to complete KYC verification proactively before you request your first withdrawal. Most casinos allow you to upload documents through the cashier or account settings menu even before you win anything. Verifying your account while you are depositing eliminates the KYC delay when you later request a payout. If your withdrawal is already pending and stuck on KYC review, check your email for a verification request from the casino, upload the requested documents through the link provided, and follow up with support after 24-48 hours if you have not received confirmation that your documents were approved.
Withdrawal rejections also occur if you attempt to withdraw to a different bank account than you deposited from. Most casinos require Trustly withdrawals to return to the same account for anti-money-laundering compliance. If you deposited from Account A and try to withdraw to Account B, the casino rejects the withdrawal and asks you to update the withdrawal method to Account A. If you closed Account A or no longer have access to it, contact support, explain the situation, upload verification documents for Account B (bank statement proving ownership), and request an exception. That process adds 24-48 hours and is not guaranteed.
KYC Verification Requirements
KYC (Know Your Customer) verification is mandatory at licensed casinos before your first withdrawal. The documents required are: photo ID (passport, driver’s license, national ID card — must be current, not expired, and show your full name, date of birth, and photo), proof of address (utility bill, bank statement, government correspondence dated within the last 90 days showing your name and residential address), and proof of payment method (for Trustly, a screenshot of your online banking dashboard showing your account number and name, or a recent bank statement showing your name and account number — some casinos skip this step for Trustly since the transfer is already bank-authenticated).
Upload clear, legible photos or scans. Blurry images, photos where text is unreadable, or documents with information obscured (other than the middle digits of a card number, which casinos ask you to obscure) get rejected. Use a scanner or a well-lit phone photo. Make sure all four corners of the document are visible in the frame. If your ID or proof of address shows a different residential address than your current address, provide both the old document and a new proof of address at your current location, along with a brief explanation in the comments field of the upload form.
The casino reviews your documents within 12-48 hours. You receive an email confirming approval or requesting resubmission if something was rejected. Approval is usually a one-time requirement: once your account is verified, future deposits and withdrawals proceed without additional document requests unless you change payment methods or hit a high-roller threshold that triggers enhanced due diligence.
Some players attempt to bypass KYC by withdrawing small amounts under the verification threshold. That strategy fails because casinos typically enforce KYC before any withdrawal, regardless of amount, or after cumulative deposits/withdrawals exceed a low threshold ($100-$500). Trying to dodge verification by making ten $50 withdrawals instead of one $500 withdrawal flags your account as suspicious and often triggers a manual review that delays all pending transactions. Complete KYC verification upfront. It takes 15 minutes to upload documents and 24-48 hours to receive approval, after which all future withdrawals process smoothly.
What happens if my Trustly deposit fails?
If a Trustly deposit fails before funds leave your bank account, no action is required — you can retry with a different deposit amount or a different payment method. If funds were debited from your bank but did not appear in your casino balance within 10 minutes, contact casino support immediately with your transaction reference number (Trustly displays this after you approve the transfer). The casino traces the deposit through their payment processor. If the deposit arrived on their end but was not credited, they credit it manually to your account within a few hours. If the deposit did not arrive on the casino’s end, Trustly initiates a refund back to your bank account, which takes 3-5 business days. Trustly transactions are reversible during the settlement window (1-2 business days) if the deposit stalled in transit. Do not retry the deposit multiple times — one failed attempt generates a transaction record that support can investigate. Multiple retries create confusion and delay resolution.
Choosing the Right Trustly Casino for You
The operator that ranks highest on Trustly withdrawal speed is not necessarily the best choice for your specific priorities. PlayAmo’s 12-hour Trustly processing is the fastest in this comparison, but its Curaçao license means weaker dispute resolution than LeoVegas’s MGA + UKGC dual licensing. Skycrown’s native AUD processing eliminates currency conversion costs, but its 1-3 day Trustly processing is slower than PlayAmo or LeoVegas. Wild Fortune’s MGA license and aggressive welcome bonus look attractive, but the $1,000 daily withdrawal limit makes it impractical for wins above a few thousand dollars.
The decision framework is: identify which factors matter most to your play style, rank operators by those factors, and accept the tradeoffs. If withdrawal speed is the priority, PlayAmo (12 hours) or LeoVegas (24 hours) rank highest. If regulatory credibility is the priority, LeoVegas, Jackpot City, Royal Panda, and Wild Fortune (all MGA or MGA + UKGC licensed) outrank Curaçao-only operators. If currency conversion cost matters, Skycrown’s native AUD processing eliminates the 2-3% round-trip markup. If mobile play is the priority, LeoVegas’s mobile-first design is the standout. If you value operational history over speed, Jackpot City’s 26 years continuous operation and Microgaming progressives offer stability.
For a first-time Trustly user who prioritises speed and does not mind Curaçao licensing, PlayAmo is the practical pick. For a player who wants premium regulatory oversight and is willing to accept 24-48 hour withdrawal timelines, LeoVegas or Royal Panda rank highest (LeoVegas for the largest game library and mobile experience, Royal Panda for transparent bonus terms). For a player depositing and withdrawing frequently in AUD and wanting to avoid conversion costs, Skycrown is the only operator in this comparison offering native AUD processing. For a player who values legacy brands with multi-decade track records, Jackpot City remains the safe, reliable choice despite slower Trustly processing and a narrower game selection.
The worst-case scenario is choosing based on headline bonus amounts without checking withdrawal limits and processing speed. Wild Fortune’s 225% welcome bonus looks impressive until you realise the $1,000 daily withdrawal cap and 1-5 day processing window mean a $10,000 win takes two weeks to cash out. Playfina’s $70,000 monthly withdrawal limit only matters if you are withdrawing in that range; for players depositing $50-$200 per session, the daily $7,000 limit is the binding constraint, and PlayAmo’s faster processing outweighs Playfina’s higher monthly cap.
Read the operator comparison table at the start of this breakdown. Identify which column matters most to your priorities (Trustly withdrawal speed, daily withdrawal limit, license tier, key differentiator). Rank operators by that column. Check the others for dealbreakers (e.g., if Skycrown’s native AUD processing is attractive, confirm you can accept 1-3 day withdrawal timelines). Pick the operator whose tradeoffs align with your play style and risk tolerance. No single operator is best across all dimensions; every choice involves compromise.
Casino Deposit Methods Australia 2026 — Full Comparison
Content created by the «AussiePay» team