Casino Sites That Accept Credit Card in Australia: The 2026 Reality Behind the Ban
 Available in AU
Credit cards were switched off for licensed online gambling in Australia on 11 June 2024. Not restricted, not discouraged. Banned outright, with a fine of up to AU$234,750 hanging over any licensed operator who ignores the rule. So when you type “casino sites that accept credit card australia” into a search bar in 2026, you’re really asking a more awkward question: what still works when the law has already closed the front door?
The short answer is messy. A handful of offshore casinos will still let you punch in a 16-digit Visa or Mastercard number. Whether that transaction actually clears is a separate matter, decided by your bank, a merchant code, and a fraud algorithm that neither you nor the casino controls. And on the rare occasion the payment does go through, your bank may quietly reclassify it as a cash advance and start charging interest from the second it lands.
This is not the page that tells you plastic is fine and here are ten “top” sites to try. Casinos are businesses, not charities, and a payment method that fails half the time while costing you extra when it succeeds is not a convenience. It’s a tax on impatience. What follows is the full picture: the ban, the loophole, the banking friction, the real cost, the operators that still take cards, and the payment methods that quietly do the same job for nothing.
The Credit Card Ban: What Changed in June 2024
On 11 June 2024, the Interactive Gambling Amendment (Credit and Other Measures) Act 2023 came into force. The law is narrow and absolute. Licensed Australian operators cannot accept credit cards, credit-related products, or digital currency for online wagering. The penalty for non-compliance is AU$234,750 per breach, enforced by the Australian Communications and Media Authority. The legislation followed years of parliamentary debate and mirrors the UK ban introduced in April 2020, which found that 76 percent of former credit card gamblers stopped borrowing to gamble entirely once the method was removed.
The stated goal is simple: stop Australians from gambling with borrowed money. Land-based casinos in Australia already banned credit cards years ago. The June 2024 amendment closed the online loophole. If you hold a licensed Australian wagering account with Sportsbet, TAB, or Ladbrokes Australia, your credit card will be declined at deposit. The rule is federal, uniform, and technically airtight for any operator holding an Australian license.
But online casinos are a different story. Australia does not license online casinos domestically. The ACMA regulates interactive gambling services under the Interactive Gambling Act 2001, but that regulation focuses on prohibiting unlicensed offshore operators from serving Australians rather than licensing local ones. There are zero ACMA-approved online casinos. The only licensed forms of online gambling in Australia are sports betting and race wagering through licensed bookmakers, and those are the operators bound by the credit card ban.
Every casino site accepting Australian players in 2026 operates offshore under licenses from jurisdictions like Curaçao, Malta, Kahnawake, or Anjouan. They sit outside the Australian licensing framework entirely. The June 2024 ban applies to licensed Australian operators. It does not technically reach offshore casinos because those casinos were never subject to Australian licensing law in the first place. That creates the gap you are here to exploit: offshore casinos accepting credit cards from Australian players are not breaking Australian law by accepting the payment, because Australian law never regulated them to begin with.
That legal distinction sounds like a loophole until your transaction gets declined for the third time in a row. The offshore exception is real, but it does not mean your Visa or Mastercard will work. Banks enforce their own rules on top of federal law, and those rules do not care whether the casino has a Curaçao license or no license at all. If the merchant code says gambling and your card says credit, most Australian banks will decline the transaction before it even reaches the casino. The legal gap is narrower than it looks once the banking layer steps in.
Is it legal to use a credit card at an offshore casino if they accept it?
Using a credit card at an offshore casino is not illegal for the player under Australian law. The June 2024 ban targets operators, not individuals. You will not be prosecuted for attempting a deposit. But legality is not the same as viability. The transaction will likely be declined by your bank, and if it goes through, the bank may classify it as a cash advance with immediate interest and fees. Legal, yes. Smart, no.
A two-year effectiveness review of the ban is scheduled after June 2026, meaning results are due in late 2026 or early 2027. There is no indication the ban will be softened or reversed. The UK review found the ban worked as intended, reducing gambling-related debt without driving players offshore in meaningful numbers. Australian policymakers are more likely to tighten enforcement than roll back the rule. Offshore casinos accepting credit cards exist in a regulatory grey zone today, but that zone is shrinking, not expanding.
Why Your Credit Card Still Gets Declined at Offshore Casinos
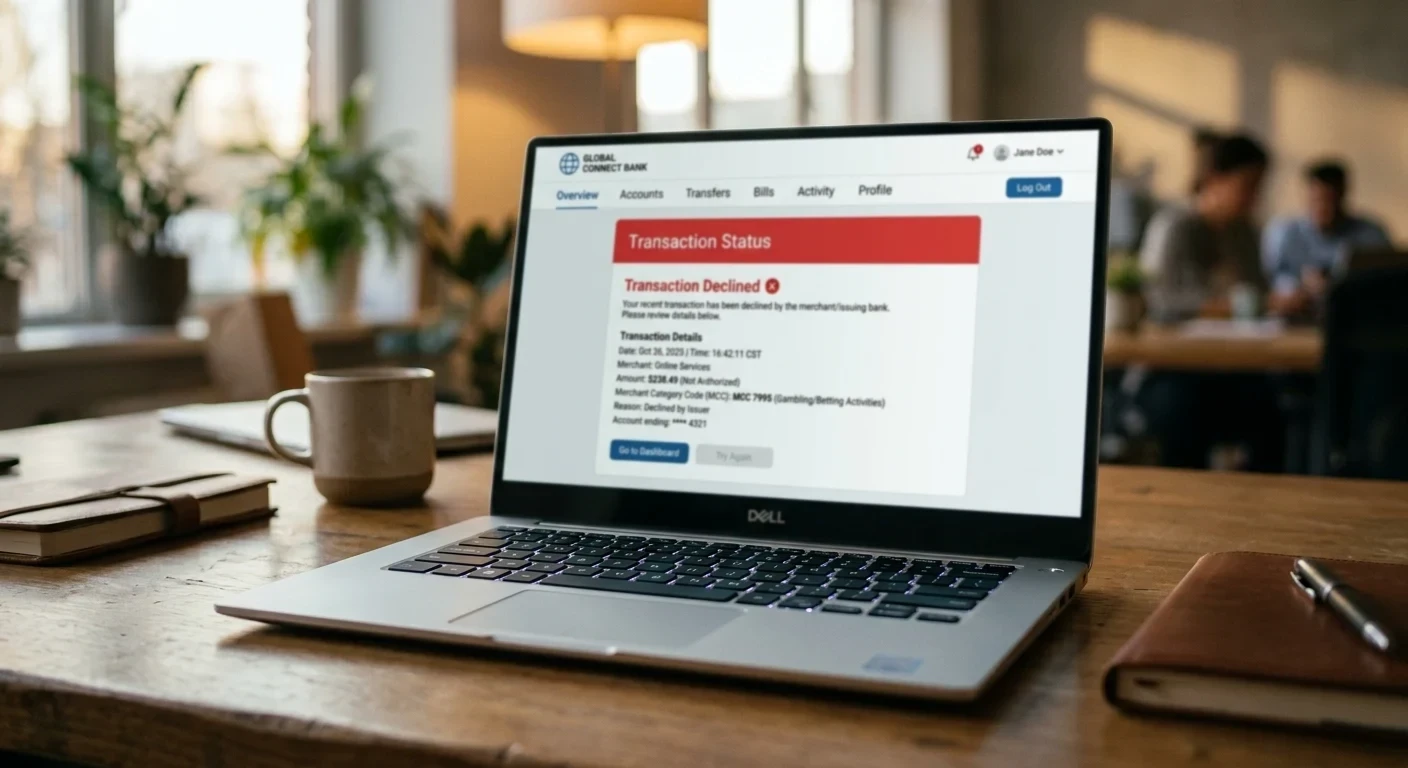
The June 2024 ban does not apply to offshore casinos. Your bank does not care. When you enter your card details at an offshore cashier and hit submit, the authorisation request travels through a payment gateway to your issuing bank. The bank receives a transaction tagged with merchant category code 7995, which flags it as gambling. That code is universal across Visa and Mastercard networks. It tells the bank exactly what you are trying to do with the money, and most Australian banks have policies to block gambling transactions on credit cards regardless of whether the merchant is licensed in Australia or operates offshore.
MCC 7995 is not new. It existed long before the June 2024 ban. What changed is how aggressively Australian banks apply it. Before the ban, blocks were inconsistent and often manually triggered by fraud algorithms or spending pattern alerts. Since the ban took effect, banks have refined their automated blocking systems to catch gambling transactions at the authorisation step. The decline happens in under three seconds. You get a generic “transaction failed” error on the casino cashier. The casino has no visibility into why. The bank does not explain itself unless you call, and even then, the explanation is vague: “Our policy does not permit gambling transactions on credit cards.”
The block is not a legal requirement for offshore casinos. Banks could allow the transaction. They choose not to because gambling transactions on credit cards carry elevated fraud risk, elevated chargeback risk, and elevated reputational risk. The 2024 legislation gave banks political cover to block everything coded as MCC 7995 on credit cards without worrying about customer complaints. The result is that even though offshore casinos are technically outside the ban’s scope, the practical effect of the ban extends to them through the banking layer.
The MCC 7995 Problem: How Banks Flag Gambling Transactions
Merchant category code 7995 is assigned to transactions where the merchant’s primary business is gambling. When a payment gateway processes a credit card deposit to an offshore casino, the gateway codes the transaction as MCC 7995 and sends it to the card network for authorisation. The card network routes the request to your issuing bank. The bank checks the MCC against its internal policy database. If the policy says “decline MCC 7995 on credit cards,” the authorisation is rejected before a cent moves. No human reviews the transaction. The decision is automated, instantaneous, and final.
Some banks apply MCC 7995 blocks only to credit cards. Others extend the block to debit cards as well. A few flag PayID transfers to merchants known to operate gambling sites. The policy varies by institution, and banks do not publish their exact rules. The only way to know whether your card will work is to test it with a small deposit, and even that is not reliable because banks update their merchant databases regularly. A card that works today may be declined tomorrow after the bank adds a particular payment gateway’s merchant ID to its block list.
Payment gateways try to obscure the merchant code by routing transactions through intermediary processors or coding them under different MCCs. This works occasionally. You will see forum posts claiming a specific casino “bypasses bank blocks” or “uses a clean gateway.” These workarounds are temporary. Once a bank identifies the intermediary processor as gambling-linked, the block gets updated and the bypass stops working. The game of cat and mouse favours the banks because they control the authorisation infrastructure.
Which Australian Banks Block Hardest (And Which Don’t)
Commonwealth Bank and Westpac are the most aggressive blockers. Both apply MCC 7995 declines to credit cards universally and extend partial blocks to debit cards for known offshore gambling merchants. ANZ and NAB are more permissive. Their credit card blocks are still in place for MCC 7995, but debit card transactions to offshore casinos succeed more often, and the banks are slower to update their merchant blacklists. If your CommBank Mastercard is declined at an offshore casino, an ANZ Visa Debit might go through, assuming the casino’s payment gateway has not been flagged yet.
Neobanks like Up and Revolut Australia apply the lightest restrictions. Up has no gambling-specific blocks on debit cards as of 2026, and Revolut’s Australian entity treats offshore gambling transactions the same as any other international payment. These banks cater to a younger, tech-savvy demographic that prioritises spending freedom over paternalistic controls. The trade-off is that neobank accounts are harder to get approved for withdrawals at some offshore casinos because they lack the brand recognition and fraud history of the big four.
| Bank | Credit Card Blocking | Debit Card Blocking | MCC 7995 Policy | Notes |
|---|---|---|---|---|
| Commonwealth Bank | Universal | Partial (known merchants) | Strict | Most aggressive blocker; frequent merchant blacklist updates |
| Westpac | Universal | Partial (known merchants) | Strict | Second most aggressive; extends blocks to some PayID transfers |
| ANZ | Universal | Low (inconsistent) | Moderate | Credit blocked, debit often succeeds; slower blacklist updates |
| NAB | Universal | Low (inconsistent) | Moderate | Similar to ANZ; debit success rate higher than CommBank/Westpac |
| Up | Not applicable (debit only) | None as of 2026 | Permissive | No gambling-specific blocks; treats offshore casinos as standard merchants |
| Revolut AU | Universal | Low | Permissive | Credit blocked per standard policy; debit succeeds for most offshore casinos |
The table reflects policies as of 2026. Banks update their blocking rules without public announcement. A debit card that works today may be declined next month after the bank receives a new merchant intelligence feed from Visa or Mastercard. There is no “safe” bank for credit card gambling deposits because every Australian bank blocks MCC 7995 on credit. The variation is in debit card treatment and how quickly the bank responds to new offshore gambling merchants entering the market.
What happens if my credit card is declined at an offshore casino?
The decline happens at authorisation. Your credit card balance is untouched. No pending charge appears. The casino’s cashier displays a generic error: “Transaction failed” or “Payment declined.” You have three options. Try a debit card instead, which banks treat differently. Try a different casino, because some use payment gateways that have not been blacklisted by your bank yet. Or switch to PayID, crypto, or a prepaid voucher, none of which rely on MCC 7995 authorisation. Calling your bank to “approve” the transaction rarely works. The block is policy, not a fraud alert, and front-line support cannot override it.
Which Australian banks block credit card gambling transactions?
All of them block credit cards for MCC 7995 transactions as of 2026. The variation is in debit card treatment. CommBank and Westpac are strictest, blocking most offshore gambling merchants on debit as well. ANZ and NAB are more permissive on debit. Neobanks like Up and Revolut apply minimal or no gambling-specific blocks to debit cards. No Australian bank allows credit card deposits to offshore casinos without friction, regardless of the casino’s license status.
The Cash Advance Trap: What It Actually Costs When Your Card Goes Through
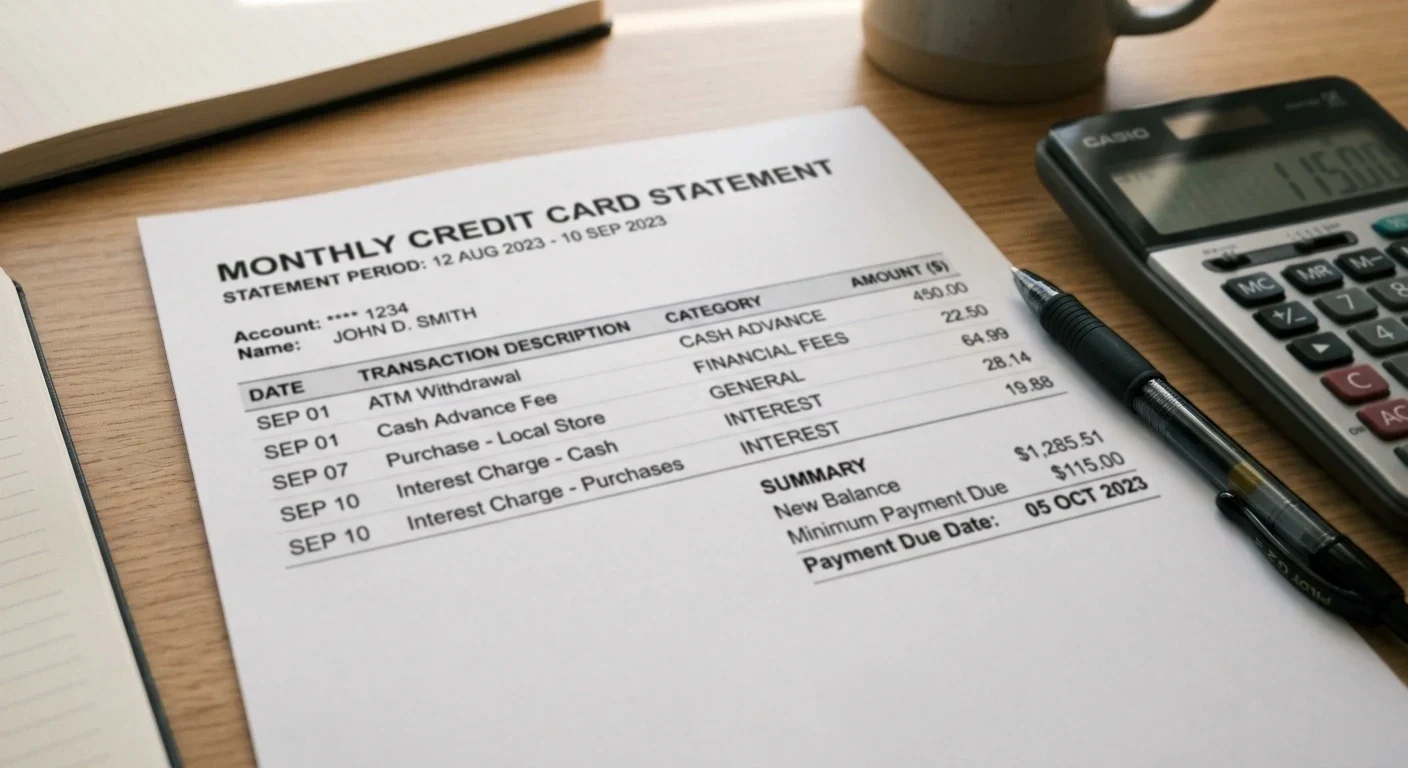
Bank blocks stop most credit card deposits at offshore casinos. Some still get through. Payment gateways rotate merchant IDs, route transactions through intermediaries in jurisdictions banks have not blacklisted yet, or use processors that code the transaction under a non-gambling MCC temporarily. When the authorisation succeeds and your credit card balance drops by the deposit amount, you might think you got away clean. Then the statement arrives, and the transaction is listed under “cash advances” instead of “purchases.”
Australian banks classify gambling transactions on credit cards as cash advances, not purchases, even when the merchant is a digital service and no physical cash changes hands. The distinction is not cosmetic. Cash advances are treated as high-risk lending under a separate fee and interest structure designed to discourage withdrawing money from ATMs or using credit for quasi-cash transactions. Gambling falls into that category because it converts credit into liquid value that can be immediately spent or withdrawn. The bank sees it as functionally identical to pulling cash from a pokies machine with your card.
A standard credit card purchase in Australia carries an interest-free period of up to 55 days if you pay the balance in full by the due date. Cash advances have no interest-free period. Interest accrues from the day the transaction clears, compounding daily. The annual percentage rate for cash advances is typically 20 to 25 percent, several points higher than the standard purchase rate of 12 to 20 percent. On top of that, the bank charges a cash advance fee, usually 2 to 3 percent of the transaction amount with a minimum of AU$3 to AU$5. That fee is non-refundable even if you pay the balance immediately.
The math is ugly. A AU$500 deposit to an offshore casino, classified as a cash advance at a 22 percent annual rate, accrues AU$0.30 in interest per day from the moment it clears. Over one month, that is approximately AU$9 in interest. Add a 3 percent cash advance fee of AU$15, and the total cost is AU$24 before you place a single bet. If you carry the balance for two months, the interest doubles to AU$18 and the total cost climbs to AU$33. A debit card deposit costs nothing. A PayID deposit costs nothing. The credit card deposit costs AU$24 minimum, and that cost is invisible at the point of transaction because the fee and interest structure are buried in your card’s terms and conditions.
Real Cost Example: A AU$500 Deposit
You deposit AU$500 to an offshore casino using a credit card. The transaction is authorised and appears on your pending charges. Three days later, it clears and your credit card balance increases by AU$500. Your bank classifies it as a cash advance. Here is what happens next.
Cash advance fee: 3 percent of AU$500 is AU$15. This fee is charged immediately and appears as a separate line item on your statement. Some banks charge a flat fee instead, typically AU$5 to AU$10. Either way, the fee is non-refundable.
Interest accrual: The AU$500 cash advance starts accruing interest at 22 percent annual rate from the day it clears. No interest-free period applies. Daily interest is calculated as 22 percent divided by 365 days, multiplied by AU$500. That is AU$0.30 per day.
Cost after one month: If you pay the balance in full after 30 days, you owe AU$500 (principal) plus AU$9 (30 days of interest at AU$0.30 per day) plus AU$15 (cash advance fee). Total: AU$524. Your AU$500 deposit cost you AU$24, a 4.8 percent surcharge before the casino takes a cent.
Cost after two months: If you carry the balance for 60 days, the interest compounds. After 30 days, the balance is AU$509 (principal plus interest), and interest is now calculated on that balance. After 60 days, total interest is approximately AU$18.20, and the total owed is AU$533.20. Your AU$500 deposit cost you AU$33.20, a 6.6 percent surcharge.
If you win and withdraw: The AU$500 credit card deposit is already on your statement accruing interest. If you win AU$1,000 and withdraw it, the withdrawal goes to your bank account or a different payment method, not back to the credit card. You still owe the AU$500 plus fees and interest. The “winnings” do not cancel the debt.
Compare that to a debit card deposit. No fees. No interest. The AU$500 is debited from your bank account balance, and if you withdraw AU$1,000, it lands in the same account. Net position: up AU$500. With the credit card, you are up AU$476 after one month or AU$466.80 after two months, assuming you paid off the credit card in full. If you lost the AU$500 instead, the debit card scenario is a AU$500 loss. The credit card scenario is a AU$524 loss after one month. You paid AU$24 for the privilege of gambling with borrowed money.
| Feature | Standard Credit Card Purchase | Cash Advance (Gambling) |
|---|---|---|
| Interest-free period | Up to 55 days | None—interest from day one |
| Interest rate (annual) | 12–20% typical | 20–25% typical |
| Cash advance fee | None | 2–3% of transaction, min AU$3–5 |
| Rewards points | Usually earned | Usually not earned |
| Example cost: AU$500 held 30 days | AU$0 (if paid in full) | AU$24 (AU$15 fee + AU$9 interest) |
The cash advance classification is not universal. Some offshore casinos use payment processors that successfully code transactions as standard purchases, at least temporarily. But you will not know which classification applies until the statement arrives. By then, the interest has already started accruing. The only way to avoid the cash advance trap entirely is to not use a credit card for gambling deposits in the first place. Debit cards, PayID, and crypto bypass the problem because they do not involve borrowing.
Are credit card deposits at offshore casinos treated as cash advances?
Most of the time, yes. Australian banks classify gambling transactions as cash advances because they treat depositing to a casino the same as withdrawing cash from an ATM. The classification happens after authorisation, so you will not know for certain until your statement arrives. If the transaction is coded as a cash advance, interest accrues from day one at a higher rate than standard purchases, and a 2 to 3 percent fee applies. No interest-free period. No rewards points. The safest assumption is that any credit card deposit to an offshore casino will be treated as a cash advance.
How much does a credit card deposit at an online casino actually cost?
A AU$500 deposit classified as a cash advance costs approximately AU$24 over one month: AU$15 in fees (3 percent) plus AU$9 in interest at 22 percent annual rate. If you carry the balance for two months, the cost climbs to AU$33. Debit card and PayID deposits cost nothing. The credit card surcharge is a hidden tax that appears only on your statement after the transaction clears.
Offshore Casinos That Still Accept Credit Cards (With Heavy Caveats)
Six offshore operators still process Visa and Mastercard deposits from Australian players as of 2026. All operate under licenses from Curaçao or similar jurisdictions. None hold ACMA approval because Australia does not license online casinos domestically. The distinction between these operators is not whether they “accept” credit cards—they all technically do—but how reliably the deposit actually goes through once your bank and the payment gateway finish negotiating.
Reliability is the wrong word. Unpredictability is more accurate. A credit card that works at Stake might be declined at BitStarz. A card that clears today might be blocked tomorrow after your bank updates its merchant database. The payment gateway each casino uses matters more than the casino itself, and those gateways rotate regularly to stay ahead of banking blocks. What follows is a snapshot of which operators nominally accept credit cards, what they charge, and what friction to expect. Treat it as a starting point for testing, not a guarantee.
| Operator | License | Credit Card Fee | Minimum Deposit | Key Friction Point | Decline Risk |
|---|---|---|---|---|---|
| Stake | Curaçao eGaming | None (casino-side) | AU$10 | High decline rate with CommBank/Westpac; bank-side cash advance risk | High |
| BitStarz | Curaçao eGaming | 2.5% | AU$20 | Transparent fee structure; gateway rotates frequently | Medium |
| PlayAmo | Curaçao eGaming (Dama N.V.) | None (casino-side) | AU$15 | Anecdotally lower decline rate with ANZ/NAB; native AUD ledger | Medium |
| Joe Fortune | Curaçao | Up to 3% | AU$20 | Highest fee in group; Australia-specific branding; high cash advance reports | High |
| Ricky Casino | Curaçao (8048/JAZ2020-013) | Not disclosed | AU$20 | Operator pushes PayID over credit cards; native AUD ledger | Medium-High |
| Skycrown | Unclear (Malta or Curaçao) | Not disclosed | Not disclosed | Launched early 2024; mobile-first; limited public fee data | Unknown |
The table ranks decline risk based on player reports from Australian forums and casino review aggregators. No operator publishes success rates because the decline happens at the banking layer, not the casino layer. The casino sees the authorisation request fail and has no visibility into why. Your bank does not report its block rate to the casino. The decline risk rating reflects patterns observed across multiple player accounts, not official statistics.
Stake
Stake launched in 2017 as a crypto-first operator and bolted on fiat payment options later to broaden its appeal beyond Bitcoin enthusiasts. The site runs under a Curaçao eGaming license and is owned by Medium Rare N.V., a Curaçao-registered entity. Stake accepts Visa and Mastercard deposits via third-party payment gateways, with a minimum deposit of AU$10, among the lowest in the offshore market. The casino does not charge a fee on credit card deposits, but your bank likely will if the transaction is classified as a cash advance.
Stake has a large Australian player base, partly due to high-profile sponsorships like the UFC and Alfa Romeo F1 team. That visibility has also made its payment gateways a priority target for Australian banks. CommBank and Westpac decline most Stake credit card deposits as of 2026. ANZ and NAB have better success rates, but still inconsistent. The site’s crypto integration is seamless—depositing with a credit card and converting to USDT or Bitcoin within the platform works around some banking friction, though the initial card authorisation is still the chokepoint.
The appeal of Stake is the AU$10 minimum. You can test whether your card works without committing a large amount. If the deposit clears, you are in. If it is declined, you have lost nothing and can pivot to crypto or a debit card. The game library exceeds 3,000 titles from providers like Pragmatic Play and Evolution Gaming. Withdrawals are fast for crypto—typically under 10 minutes for Bitcoin—but fiat withdrawals via bank transfer take 3 to 5 business days, assuming you passed identity verification.
BitStarz
BitStarz has been operational since 2014, making it one of the longer-running operators in the crypto-fiat hybrid space. The site is licensed by the Curaçao Gaming Control Board under the old master-license framework, currently transitioning to the reformed Curaçao Gaming Authority structure introduced in 2024. BitStarz is operated by Direx N.V., another Curaçao entity. The casino charges a transparent 2.5 percent processing fee on credit card deposits, which is industry-standard for covering gateway costs.
The minimum deposit is AU$20. The fee structure is disclosed upfront in the cashier, so you know the AU$20 deposit will cost AU$20.50 before you confirm. That transparency is rare. Most offshore casinos bury fees in terms and conditions or rely on the bank’s cash advance classification to extract the cost without directly charging it. BitStarz takes its cut openly. Whether that is more honest or just a different flavour of the same surcharge depends on your perspective.
BitStarz runs a dual-currency model. Fiat deposits via credit card or bank transfer settle in AUD. Crypto deposits settle in Bitcoin, Ethereum, Litecoin, or USDT. Withdrawals via crypto are processed in approximately 10 minutes. Fiat withdrawals take 1 to 3 business days. The game library exceeds 3,000 titles, weighted toward slots from NetEnt, Microgaming, and Pragmatic Play. The site has a strong reputation for actually paying out winnings, which matters more than game selection when you are dealing with an offshore operator outside Australian regulatory oversight.
Credit card decline rates at BitStarz are moderate. The payment gateway rotates regularly, so a card declined today might work next month after the gateway switches to a new merchant ID. CommBank remains the hardest to get through. ANZ and NAB debit cards have better success rates. The 2.5 percent fee is predictable. The cash advance risk from your bank is not.
PlayAmo
PlayAmo operates under a Curaçao eGaming license issued to Dama N.V., a Curaçao entity that runs multiple sister brands under the same corporate umbrella. The casino does not charge a fee on credit card deposits, which gives it a pricing advantage over BitStarz. The minimum deposit is AU$15, splitting the difference between Stake’s AU$10 and BitStarz’s AU$20. PlayAmo accepts AUD natively, so there are no foreign exchange spreads hiding in the conversion rate when you deposit or withdraw.
Anecdotal reports from Australian players suggest PlayAmo has a lower credit card decline rate than Stake, particularly with ANZ and NAB cards. This is not verified data—no casino publishes its authorisation success rate—but the pattern shows up consistently enough across forum threads and review sites to be worth noting. The lower decline rate may be due to PlayAmo’s payment gateway flying under the radar longer before Australian banks flag it, or it may be chance. Either way, if your card has been declined at Stake or Joe Fortune, PlayAmo is worth testing before giving up on credit cards entirely.
The game library exceeds 3,000 titles, including live dealer tables from Evolution Gaming and slots from NetEnt, Microgaming, and Pragmatic Play. Withdrawals to bank accounts take 3 to 5 business days after identity verification. Crypto withdrawals are faster but require converting your AUD balance to Bitcoin or USDT first, which adds a step. The native AUD ledger is the main draw. You deposit AU$100, you see AU$100 in your account, and you withdraw AU$100 plus winnings without a currency conversion fee taking a slice.
Joe Fortune
Joe Fortune operates under a Curaçao license and brands itself specifically for the Australian market. The site design, support hours, and promotional language are tailored to AEST time zones and Australian cultural references. The minimum deposit is AU$20, and the credit card processing fee ranges up to 3 percent depending on which payment gateway processes the transaction. That is the highest fee structure in this group, and the fee is not always disclosed clearly in the cashier before you confirm the deposit.
Player reports suggest Joe Fortune has a high incidence of cash advance classification on successful credit card deposits. Whether that is due to the specific payment processors Joe Fortune uses or simply the nature of how Australian banks treat offshore gambling transactions is unclear. Either way, a deposit that clears at Joe Fortune is more likely to show up as a cash advance on your statement than a deposit at PlayAmo or BitStarz, based on aggregated player feedback from review sites and forums. That means higher interest charges and a cash advance fee on top of the casino’s up-to-3-percent processing fee.
The game library is smaller than Stake or BitStarz, estimated at 1,000 to 2,000 titles. The focus is on pokies and live dealer games rather than breadth of selection. Crypto deposits are accepted—Bitcoin, Litecoin, Ethereum, and Bitcoin Cash—but the site’s fiat-first branding suggests most Australian players are depositing with cards or bank transfers. Withdrawals take 3 to 5 business days for fiat, faster for crypto.
The Australia-specific branding is the double-edged sword. It makes the site feel more familiar and accessible to Australian players unfamiliar with offshore casinos. It also makes Joe Fortune a higher-priority target for Australian banks refining their MCC 7995 blocking algorithms. CommBank and Westpac decline most Joe Fortune credit card deposits as of 2026. ANZ and NAB are hit-or-miss. The combination of high fees, high cash advance risk, and high decline rates makes Joe Fortune the least attractive credit card option in this group unless you specifically value the Australia-focused branding and support.
Ricky Casino
Ricky Casino launched in 2023 under Curaçao Master Licence 8048/JAZ2020-013. The site is purpose-built for Australian players, with a native AUD ledger that eliminates foreign exchange spreads. Ricky accepts Visa and Mastercard deposits, but the operator actively promotes PayID and POLi as preferred methods in the cashier flow. Credit card fees are not disclosed publicly, which suggests they are either absorbed by the casino or variable depending on the payment gateway used at the time of deposit.
The minimum deposit is AU$20. Credit card decline rates are moderate to high, though not as severe as Stake or Joe Fortune. The bigger tell is that Ricky’s own cashier design pushes PayID to the top of the payment method list and buries credit cards lower in the menu. When a casino deprioritizes its own credit card option, it is usually because the authorisation success rate is low enough that the casino would rather route you to a method that works reliably. PayID deposits at Ricky are instant, and withdrawals land in 1 to 4 hours after identity verification, which is significantly faster than the 3-to-5-day fiat withdrawal window at most offshore casinos.
The game library exceeds 4,000 titles, weighted toward pokies from Pragmatic Play and NetEnt. Live dealer games are provided by Evolution Gaming. The site launched recently enough that its payment gateway infrastructure is still evolving. A credit card declined today might work next month after Ricky switches processors, or it might be blocked permanently after your bank flags the new gateway. The native AUD ledger and fast PayID withdrawals make Ricky a strong option if you are willing to skip credit cards entirely. If you insist on testing a credit card, the AU$20 minimum limits your exposure.
Skycrown Casino
Skycrown launched in early 2024 and operates under a license that is ambiguous in public sources. Some listings identify it as a Malta Gaming Authority license, others as Curaçao. If the MGA license is accurate, Skycrown would be the only operator in this group subject to stricter European regulatory oversight. If it is Curaçao, it sits alongside the rest as a lightly regulated offshore operator. The license ambiguity is worth verifying directly on the casino’s site before depositing, because MGA-licensed operators have higher compliance standards for player protection and dispute resolution.
Skycrown accepts Visa and Mastercard deposits. The minimum deposit and credit card fees are not disclosed in public sources, so expect the industry norm of AU$20 to AU$30 minimum and either no fee or a 2-to-3-percent processing charge. Credit card acceptance was confirmed as of September 2026 per multiple casino review sites, but the decline rate is unknown because the site is too new to have accumulated enough player feedback. The mobile-first design prioritises PayID, POLi, and crypto over credit cards, which suggests the operator expects card deposits to be unreliable.
The game library size is not disclosed. Deposits are instant for all methods. Withdrawals are not independently verified but likely follow the 3-to-5-day fiat window standard for offshore casinos. Skycrown is the wild card in this group. If you have exhausted the other five operators and still want to test a credit card, Skycrown is the newest option with the least banking-layer friction simply because Australian banks have not had time to blacklist its payment gateways yet. That advantage is temporary.
Can I use a credit card at online casinos in Australia in 2026?
Technically, yes, at offshore casinos outside the June 2024 ban. Practically, expect frequent declines due to MCC 7995 banking blocks. CommBank and Westpac decline most transactions. ANZ, NAB, and neobanks have better success rates but are inconsistent. If a deposit clears, your bank will likely classify it as a cash advance with immediate interest and a 2-to-3-percent fee. Debit cards, PayID, and crypto avoid both the decline risk and the cash advance cost.
Why do some offshore casinos still accept credit cards if they are banned in Australia?
The June 2024 ban applies only to licensed Australian operators. Offshore casinos operate under foreign licenses and are not bound by Australian law. They accept credit cards because the payment method is familiar to players and lowers the barrier to deposit. Whether the transaction succeeds depends on your bank, not the casino. Offshore operators are not breaking Australian law by offering credit card deposits to Australian players because they were never subject to Australian licensing in the first place.
What to Use Instead: Debit Cards, PayID, and Crypto
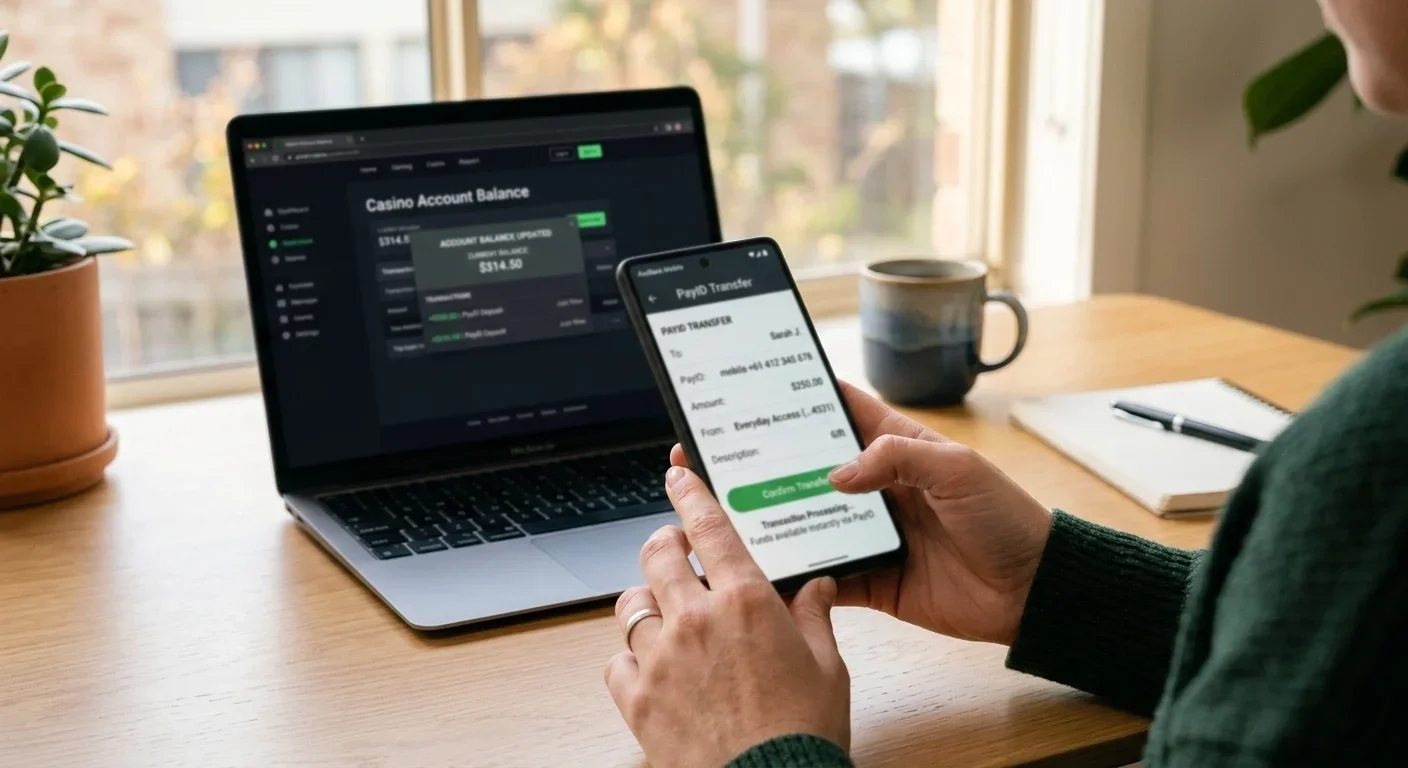
Credit cards failed as a reliable payment method for offshore casinos the moment Australian banks tightened MCC 7995 enforcement. Three alternatives work better: debit cards draw from money you already have rather than borrowing, PayID uses the New Payments Platform for instant bank-to-bank transfers, and cryptocurrency bypasses traditional banking infrastructure entirely. All three avoid the cash advance trap. All three have higher authorisation success rates. The question is which one fits your tolerance for setup friction and withdrawal speed.
| Method | Deposit Speed | Withdrawal Speed | Fees | Bank Blocking Risk | Best For |
|---|---|---|---|---|---|
| Credit Card | Instant (if authorised) | Not supported | 0–3% + cash advance fee + interest | High (universal MCC 7995 block) | Testing small deposits if other methods unavailable |
| Debit Card | Instant | 3–5 business days | Usually none | Low to medium (varies by bank) | Familiar card-based flow without borrowing |
| PayID | Under 60 seconds | 1–4 hours | None | Low (some banks flag offshore merchants) | Fastest deposit and withdrawal with no fees |
| Crypto (USDT TRC-20) | Under 60 seconds | 5–30 minutes | Network fee (minimal for USDT TRC-20) | None | Fastest withdrawal, no banking friction |
| Neosurf / Paysafecard | Instant | Not supported (cash-out via separate method) | None at deposit | None (purchased with cash) | Privacy-focused, no bank trail |
The table reflects typical performance as of 2026. Individual casino processing times vary, particularly for fiat withdrawals. Crypto withdrawal speed depends on network congestion. PayID withdrawal speed depends on the casino’s internal approval process and whether you have completed identity verification.
Debit Cards: The Obvious Swap
A Visa or Mastercard debit card works identically to a credit card at the deposit screen. You enter the 16-digit card number, expiry date, and CVV, and the authorisation request travels through the same payment gateway to your bank. The difference is the bank checks your account balance instead of your credit limit, and the transaction is not classified as a cash advance because you are not borrowing. The money is debited immediately from your linked bank account. No interest accrues. No cash advance fee applies.
Australian banks block some debit card transactions to offshore gambling merchants using the same MCC 7995 flag they apply to credit cards, but the enforcement is inconsistent. CommBank and Westpac extend partial blocks to debit cards for known offshore casinos. ANZ and NAB are more permissive. Neobanks like Up and Revolut Australia apply minimal or no gambling-specific blocks to debit cards as of 2026. A debit card from ANZ or a neobank has a significantly higher success rate than a credit card from any Australian bank.
The authorisation success rate is still not 100 percent. Payment gateways rotate, banks update their merchant blacklists, and what works today may be blocked tomorrow. But the decline risk with a debit card is lower than with a credit card, and when the transaction does clear, the cost is zero beyond the deposit amount itself. No hidden fees. No interest. The withdrawal process for debit cards mirrors credit cards: most offshore casinos do not support withdrawals back to the card, so winnings land in your bank account via bank transfer, which takes 3 to 5 business days after identity verification.
If you already own a Visa or Mastercard debit card linked to an Australian bank account, test it before exploring PayID or crypto. The setup friction is zero. The deposit flow is familiar. The failure mode—a declined transaction—costs you nothing. If the debit card works, you have a reliable deposit method with no surcharge. If it is blocked, PayID is the next step.
PayID: Instant Transfers Without the Drama
PayID is an identifier tied to your Australian bank account that lets you send and receive money via the New Payments Platform without entering BSB and account numbers. You create a PayID through your bank’s app or website, usually using your mobile number or email address. Once set up, you select PayID at the casino cashier, enter your PayID, confirm the deposit amount, and approve the payment in your banking app. The casino receives the funds in under 60 seconds and credits your account instantly.
PayID bypasses MCC 7995 entirely because the transaction is coded as a standard bank transfer, not a card payment. Your bank sees an NPP transfer to a business account. Some banks flag the recipient as a known gambling merchant and decline the transfer, but this is rare compared to the universal credit card blocks. CommBank and Westpac are most likely to flag offshore casino PayID transfers. ANZ, NAB, and neobanks rarely block them. If your bank does decline the transfer, you get an error message in your banking app before the money leaves your account. No pending charge. No fee.
The deposit cost is zero. No processing fee from the casino. No cash advance fee or interest from your bank. The AU$100 you transfer is the AU$100 that lands in your casino account. Withdrawals via PayID are significantly faster than fiat withdrawals to a debit card. The typical processing window is 1 to 4 hours after the casino approves the withdrawal, assuming you have completed identity verification. Some offshore casinos process PayID withdrawals in under an hour during business hours. That speed advantage alone makes PayID the preferred method for Australian players who plan to withdraw winnings rather than gamble until the balance hits zero.
The setup friction is minimal if your bank supports PayID, which every major Australian bank does as of 2026. You create the PayID once in your banking app, and it works at every casino that accepts PayID. The method is Australia-specific, so offshore casinos serving multiple regions may not support it. All six operators listed in the previous section accept PayID. If you deposit AU$500 via PayID and win AU$1,000, you can withdraw AU$1,000 via PayID back to the same bank account in a few hours. With a credit card, you deposit AU$500, pay AU$24 in fees and interest, and wait 3 to 5 days for a bank transfer withdrawal. PayID eliminates both the cost and the delay.
Crypto: No Banking Friction
Cryptocurrency deposits bypass the entire banking layer. You transfer Bitcoin, Ethereum, USDT, or another supported coin from your wallet to the casino’s deposit address. The transaction is confirmed on the blockchain, and the casino credits your account. No bank authorisation. No MCC 7995 flag. No cash advance classification. The casino receives the funds in 10 to 60 minutes depending on network congestion, and your account is credited in an equivalent AUD value based on the exchange rate at the time of deposit.
USDT TRC-20 is the fastest and cheapest option for Australian players new to crypto. USDT is a stablecoin pegged to the US dollar, so the value does not fluctuate like Bitcoin or Ethereum. The TRC-20 variant runs on the Tron blockchain, which has minimal transaction fees and confirms in under 60 seconds. You buy USDT on an Australian exchange like CoinSpot or Swyftx, transfer it to a wallet like Trust Wallet or Exodus, and send it to the casino’s deposit address. The learning curve is steeper than PayID, but the friction disappears after the first deposit.
Crypto withdrawals are the fastest option in the offshore casino space. Most operators process Bitcoin and USDT withdrawals in 5 to 30 minutes, compared to 1 to 4 hours for PayID and 3 to 5 days for bank transfers. You request the withdrawal in the casino cashier, paste your wallet address, and the funds land in your wallet after blockchain confirmation. From there, you can hold the crypto, transfer it back to an Australian exchange, and sell it for AUD if you want the money in your bank account. The exchange-to-bank-account step adds another 1 to 2 business days, but the casino-to-wallet step is nearly instant.
The cost structure is transparent. Crypto deposits at offshore casinos are fee-free on the casino side. The only cost is the network fee, which is negligible for USDT TRC-20—typically under AU$1. Bitcoin network fees fluctuate based on congestion, ranging from AU$2 to AU$10 per transaction. Ethereum fees are higher and less predictable. Withdrawals carry the same network fee structure. There are no hidden surcharges, no cash advance fees, and no interest. You deposit AU$500 worth of USDT, and AU$500 lands in your casino account minus the AU$1 network fee.
The barrier is familiarity. If you have never bought crypto before, the process of setting up an exchange account, completing identity verification, buying USDT, transferring it to a wallet, and sending it to a casino feels like learning a new language. If you have used crypto before, it is the most frictionless deposit and withdrawal method available. The decision comes down to whether you value speed and reliability enough to invest an hour in setup. For players depositing and withdrawing frequently, crypto is the optimal choice. For players making one or two deposits, PayID is easier.
What’s the difference between using a credit card and a debit card at an online casino?
A credit card borrows money from the bank and is almost always declined by Australian banks for offshore casino deposits due to MCC 7995 blocks. If the deposit clears, it is classified as a cash advance with immediate interest and a 2-to-3-percent fee. A debit card draws from your bank account balance, costs nothing beyond the deposit amount, and has a lower decline rate because banks are less aggressive about blocking debit transactions. Debit is the same flow as credit but without the borrowing cost.
Withdrawal Reality Check
Offshore casinos that accept credit card deposits do not support credit card withdrawals. This is not a policy specific to Australian players. It is a structural limitation of how card networks handle gambling transactions. Visa and Mastercard permit deposits to licensed gambling merchants in jurisdictions where it is legal, but they prohibit refunds or payouts coded as gambling winnings back to the card. The chargeback risk is too high, and the card networks do not want to be in the business of facilitating gambling payouts where they can be reversed through a dispute.
When you win and request a withdrawal, the offshore casino offers bank transfer, PayID, crypto, or another non-card method. If you deposited via credit card, your winnings land in your bank account via a separate transfer, typically 3 to 5 business days after approval. The original credit card deposit remains on your credit card statement as a purchase or cash advance. You owe that balance to the bank regardless of whether you won or lost at the casino. The winnings do not cancel the debt.
The practical implication is that depositing with a credit card locks you into a withdrawal method you did not choose at deposit. Most players assume the withdrawal will reverse the deposit route, but that is not how offshore casinos work. You deposit AU$500 on a credit card, win AU$1,000, and request a withdrawal. The casino sends AU$1,000 to your bank account via wire transfer. You still owe the bank AU$500 plus cash advance fees and interest on your credit card. If you lost the AU$500 instead, the credit card debt is still there, plus fees and interest. The withdrawal asymmetry makes credit cards a poor choice even when the deposit succeeds.
Visa, Mastercard, or Amex: Does It Matter?
Visa and Mastercard dominate the offshore casino payment space. American Express is rarely accepted. Discover and Diners Club are effectively non-existent. If you plan to use a credit or debit card at an offshore casino, assume you are working with Visa or Mastercard. Anything else is a waste of time.
Visa and Mastercard apply the same MCC 7995 merchant category code to gambling transactions. The card network does not block the transaction—your issuing bank does, using the MCC as a flag. Visa transactions to offshore casinos are declined at the same rate as Mastercard transactions when the same bank issues both cards. The network makes no difference. The issuing bank is the variable that matters. A CommBank Visa and a CommBank Mastercard will both be declined at the same offshore casino. An ANZ Visa has a better chance than a CommBank Visa, not because Visa is more permissive, but because ANZ is.
American Express operates its own payment network and historically applied stricter merchant category policies than Visa and Mastercard. Amex charges higher processing fees to merchants, and many offshore casinos do not accept it at all. The few that do accept Amex see higher decline rates than Visa or Mastercard because Amex’s internal fraud algorithms flag gambling transactions more aggressively. If your only card is an Amex, skip the offshore casino credit card deposit entirely. Open a debit card account with ANZ or a neobank, or use PayID.
Prepaid Visa or Mastercard gift cards are a workaround some players attempt. You buy a prepaid card at a retail store, load it with AU$100 or AU$200, and use it to deposit at an offshore casino. The card is not linked to your bank account, so there is no risk of overdraft or credit card debt. The problem is identity verification. Offshore casinos require the card used for deposit to be in the player’s name for anti-money-laundering compliance. A prepaid gift card has no name on it. You might get the deposit through, but when you try to withdraw, the casino will ask for a photo of the card showing your name. You cannot provide it because the card is anonymous. The withdrawal gets blocked, and your winnings are stuck until you provide an alternative payment method that passes verification.
Prepaid cards work as a one-time deposit method if you plan to lose the balance and never withdraw. If you plan to win and cash out, the prepaid card creates more problems than it solves. Use a debit card in your name or switch to PayID.
The “Real Money” Redundancy
Every deposit to an online casino is real money. The phrase “credit card casinos real money” appears in search queries because players want to distinguish between social casinos that use virtual currency and gambling sites that take actual deposits. The distinction is valid, but once you are looking at offshore casinos like Stake, BitStarz, or PlayAmo, the “real money” qualifier is redundant. All six operators listed in this guide accept real money deposits and pay out real money winnings. There are no play-money modes. There are no virtual-currency wrappers.
The search intent behind “real money credit card casino” is usually “which casinos accept real money deposits via credit card and let me cash out real money.” The answer is all of them, subject to the banking blocks and cash advance costs detailed earlier. If the query is trying to filter out scam sites that take deposits but never pay out, the filter you need is operator reputation, not the “real money” label. Offshore casinos with Curaçao licenses are lightly regulated. Some pay out reliably. Some delay withdrawals, demand excessive identity documents, or void winnings on technicalities buried in terms and conditions.
The operators in this guide—Stake, BitStarz, PlayAmo, Joe Fortune, Ricky, Skycrown—have track records of processing withdrawals, even if the speed and customer service quality vary. That does not make them safe in the sense of being regulated by ACMA or protected by Australian consumer law. It makes them less likely to simply steal your deposit than an unlicensed site with no public reputation. The “real money” distinction does not protect you. Due diligence on the operator’s payout history does.
What Happens Next: The 2026 Effectiveness Review
The Interactive Gambling Amendment (Credit and Other Measures) Act 2023 mandates a two-year effectiveness review after June 2026. That puts the review window in late 2026 or early 2027. The review will assess whether the credit card ban reduced gambling-related harm, whether it drove players to offshore operators in significant numbers, and whether unintended consequences emerged that warrant adjusting the law.
The UK provides a precedent. The UK Gambling Commission banned credit card gambling in April 2020. A 2022 review found that 76 percent of former credit card gamblers stopped using credit to gamble entirely after the ban. The remaining 24 percent switched to debit cards or other methods, but the overall volume of gambling on credit dropped sharply. Problem gambling indicators linked to credit card use declined. The ban was deemed effective and remains in force as of 2026 with no signs of reversal.
Australian policymakers are watching the UK model. The June 2024 ban was explicitly designed to align Australia with UK policy. The two-year review is a formality required by the legislation, not a signal that the ban is under reconsideration. If the Australian review finds similar results to the UK—reduced gambling debt, no significant offshore migration—the ban will likely be extended or strengthened rather than softened. Potential expansions include stricter enforcement against offshore operators advertising to Australian players, tighter bank-side controls on debit card gambling transactions, or restrictions on buy-now-pay-later services being used for gambling deposits.
The review is not a referendum on whether credit cards should be unbanned. It is an assessment of whether the current ban is working as intended and whether additional measures are needed. For players relying on credit cards to deposit at offshore casinos in 2026, the regulatory direction is tightening, not loosening. The offshore loophole will not be closed directly because Australia does not have jurisdiction over Curaçao-licensed operators, but the banking layer will continue to tighten MCC 7995 enforcement, and the practical effect will be the same as a direct ban.
The window for credit card deposits at offshore casinos is shrinking. Payment gateways will continue rotating to stay ahead of banking blocks, and some transactions will continue to clear for months or years. But the long-term trend is toward debit cards, PayID, and crypto as the only reliable deposit methods for offshore casinos serving Australian players. If you are reading this in 2026 and your credit card still works at one of the six operators listed, treat it as temporary and have a backup method ready.
Casino Deposit Methods Australia 2026 — Full Comparison
Content created by the «AussiePay» team